 Reviewed by
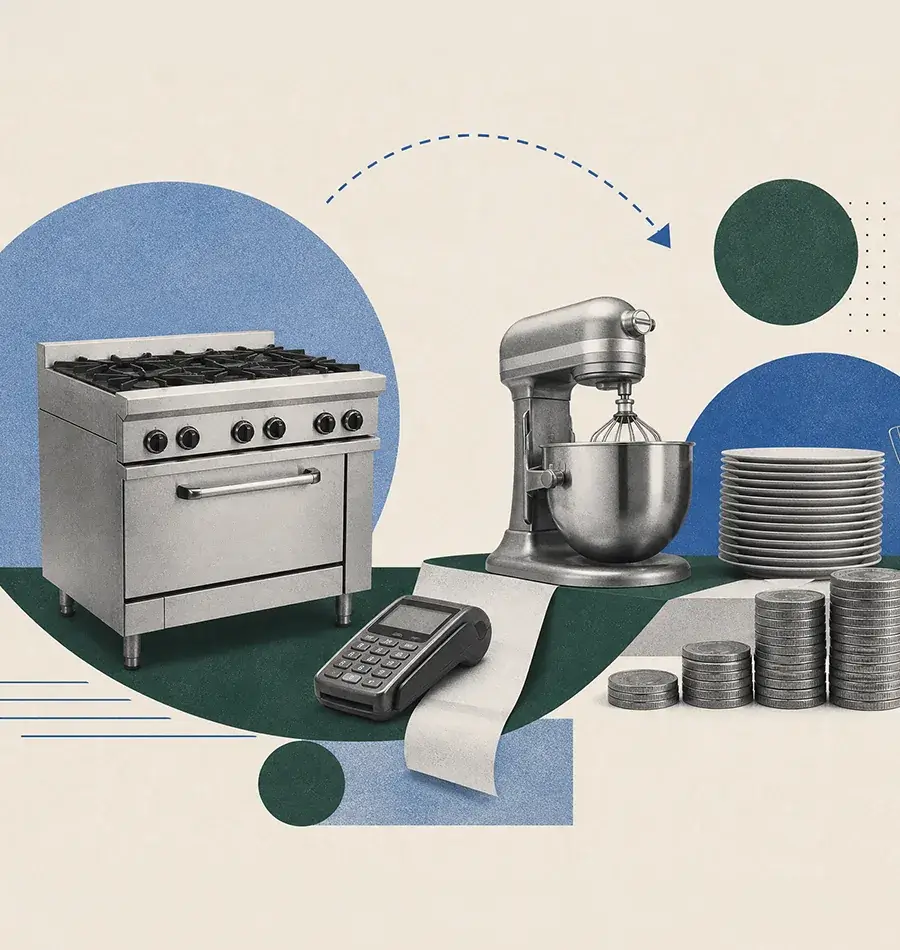
Sooner or later, every restaurant faces the same call: a walk-in dies, the line needs a faster oven, or a second location needs a full kitchen. Paying cash drains the reserves you need for payroll and slow seasons, so most established operators finance the equipment instead. The real question isn't whether to finance, it's how, and whether to buy or lease. I've spent years helping restaurant owners finance equipment, and the ones who choose well start with the numbers: what the gear costs, what financing costs, and how the tax break changes the total cost.
Below, I walk through 2026 equipment costs by category, the buy-vs-lease decision (with a calculator you can run), your financing options, and the Section 179 tax break that makes owning cheaper than it looks.
Why Financing Restaurant Equipment Makes Sense for an Established Operator
You could pay cash, but that rarely makes sense once you're up and running. Financing spreads the cost of a depreciating asset over manageable monthly payments and keeps your cash where it does the most good. For an established restaurant, the case is clear:
Protect working capital. Keep your cash for payroll, inventory, and rent instead of sinking it into a single walk-in. Preserving working capital is what keeps day-to-day operations steady.
Smooth cash flow. Fixed monthly payments are easier to plan around than a five-figure hit, and they keep your cash flow predictable.
Keep credit open. Financing equipment separately leaves your business line of credit free for emergencies.
Upgrade on schedule. Replace aging equipment or expand to a new location without waiting to save up.
The point isn't affordability; it's matching a long-lived asset to a payment plan while keeping your options open.
What Commercial Kitchen Equipment Costs in 2026
Before you size your financing, know what you're buying. A full commercial kitchen commonly runs from about $75,000 to over $250,000 in 2026, depending on concept and size, and the equipment usually breaks into four categories:
| Category | Example equipment | Typical 2026 cost | Financing note |
|---|---|---|---|
| Cooking | Commercial ovens, ranges, fryers, griddles, grills, commercial mixers | A six-burner range with oven runs about $3,000 to $8,000; a full cooking line runs $15,000 to $35,000 | Longest-life gear; strong buy-and-finance candidates |
| Refrigeration | Walk-in coolers, walk-in refrigerators, freezers, ice machines, reach-ins, prep tables, dishwashers | Reach-ins and walk-ins run about $3,500 to $25,000; a full refrigeration setup $12,000 to $25,000 | Mission-critical; warranty length can guide the lease term |
| Beverage and bar | Espresso machines, blenders, draft and bar systems | Commercial espresso machines run about $1,000 to $19,000 | Fast-evolving; often better to lease and upgrade |
| Point of sale | Point-of-sale systems (hardware plus software) | POS hardware runs about $300 to $2,500, plus $50 to $300 a month for software | Often financed short-term or on a line of credit |
Prices vary by brand, capacity, and whether you buy new or used, so use your own quotes to size the financing you need. If you're outfitting a beverage-forward concept, our guide to coffee shop financing digs into the espresso and bar setup.
Section 179 and the Tax Benefits of Financing Equipment
This is what makes buying cheaper than the sticker price suggests: Section 179 lets you deduct the full purchase price of qualifying equipment the year you put it in service, and financed equipment still qualifies. For 2026, you can deduct up to $2,560,000, with the deduction phasing out above $4,090,000 in purchases, and 100% bonus depreciation covers anything beyond that limit.
Say you buy $25,000 of cooking equipment and your marginal tax rate is 24%:
| Equipment price | $25,000 |
|---|---|
| Section 179 deduction | $25,000 |
| Tax savings (24% rate) | $6,000 |
| Net cost after the deduction | $19,000 |
You finance the purchase, keep your cash, and still write off the full amount this year. Remember, your Section 179 deduction can't exceed your taxable business income for the year. If the equipment costs more than the business earned, you deduct up to that income and carry the rest forward.
Talk to your accountant about your situation, but for many established restaurants, Section 179 can make purchasing equipment more attractive than entering a true lease.
Should You Buy or Lease Restaurant Equipment
This is the decision that drives everything else. Buying with an equipment loan means you own the gear and can write off the full cost, but you carry the asset as it ages. Leasing keeps monthly payments and up-front costs lower and lets you upgrade often, but you pay more over time and may not own anything at the end. Three questions settle it:
How long will you keep it? Long-life gear you'll run for a decade (ovens, walk-ins) usually favors buying. Fast-changing tech you'll upgrade in a few years often favors leasing.
How's your cash flow? Leasing protects cash with lower payments and little or no down payment. Buying costs less over the full life if you can handle the payments.
How does it affect your taxes? Buying lets you take the Section 179 deduction on the full price this year; lease payments are deductible as an operating expense instead.
Leases come in two main types: a fair market value (FMV) lease, where you return the equipment or buy it at its residual value, and a $1 buyout lease, where you own it for a dollar at the end (with higher monthly payments). Weigh the total cost of each path against how long you'll keep the equipment.
Restaurant Equipment Financing Options
Once you've settled buy versus lease, match the financing to the purchase. The main restaurant equipment financing options, from restaurant equipment loans and leases to SBA loans, compare like this:
| Option | Funding speed | Typical rate or term | Own it? | Best fit |
|---|---|---|---|---|
| Equipment loan | 1 to 5 days | Starting at 6% APR, 1 to 6 years | Yes | High-value, long-life gear |
| Equipment leasing | 1 to 5 days | Built into the monthly payment | Return or buy at lease end | Fast-upgrading or cash-tight |
| SBA loan | 30 to 90 days | Long terms, lower rates | Yes | Best rates for strong credit |
| Business line of credit | Same day to days | Revolving, variable rate | Yes | Repeat or smaller purchases |
| Short-term loan | As fast as same day | Higher rate, 6 to 36 months | Yes | Fast cash, thinner credit |
| Vendor or dealer financing | At purchase | Varies by vendor | Usually | A single item, fastest route |
Equipment Loans
An equipment loan finances a specific machine, and the equipment itself serves as collateral, which often means up to 100% financing and no separate down payment. Best for established operators with decent credit buying high-cost gear like commercial ovens or walk-in refrigerators.
Equipment Leasing
Leasing restaurant equipment lets you use it for a set term with lower up-front cost, then return, renew, or buy it under the lease agreement. Best when you want to preserve cash or expect to upgrade before the equipment wears out.
SBA Loans
SBA loans (7(a) for equipment and working capital, 504 when real estate is involved) offer the longest terms and lowest rates, backed by the U.S. Small Business Administration. The tradeoff is a longer application, so they suit established businesses with strong financial statements that can wait a few weeks.
Business Line of Credit
A business line of credit gives you revolving access to funds and charges interest only on what you draw. It's a flexible fit for smaller or repeat equipment purchases and for smoothing cash flow between them.
Short-Term Loans and Other Options
When speed matters, short-term loans from online lenders fund fast with looser credit requirements, at higher rates and shorter repayment terms. Vendor and dealer financing can close a single-item purchase on the spot, and for needs beyond a single machine, a broader restaurant business loan or small business loan can bundle equipment with working capital. Merchant cash advances are the most expensive route and are worth using only as a last resort.
How To Choose the Right Lender and Compare Rates
With a few years of history and steady revenue, you can command better terms, so shop the offer, not just the monthly payment. Weigh these factors:
Compare APR, not the monthly payment
A low monthly payment can hide a high rate over a longer term, so compare the APR and total cost across lenders.
Match the lender to your timeline
Traditional banks offer the lowest interest rates but move slowly; online lenders and specialized equipment lenders fund in days at higher rates.
Read the fees and end terms
Check origination fees, prepayment penalties, and, for a lease, the end-of-term buyout.
Weigh service and transparency
Work with financing companies known for clear terms and steady support.
What You Need To Qualify and Apply
Established restaurants qualify more easily than new ones because lenders can see real revenue and a track record. Expect a credit decision to weigh your credit score, time in business, and annual revenue, and gather this before you apply:
Financial statements. Profit and loss statements, a balance sheet, and recent bank statements.
Tax returns. Usually, the last two years of business tax returns.
Equipment quote. An invoice or quote for the equipment you're financing.
Business plan. For SBA or bank loans, a current business plan showing how the equipment fits your operation.
Strong revenue and a solid credit score earn the best rates. If you've hit a rough patch, bad credit doesn't rule you out, but expect a higher rate or a lease instead of a bank loan.
Minimum Qualifications

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
How To Manage Your Financing After You're Funded
Getting funded is the start. Manage the financing so it works for you:
Match payments to your season
Line up repayment terms with your cash flow so slow months don't strain you.
Track the asset for taxes
Keep records so you can claim the Section 179 deduction and any tax benefits at filing.
Refinance or pay off early when it helps
If your credit or rates improve, revisit the loan.
Common Financing Mistakes To Avoid
Even experienced operators trip on the same things:
Chasing the low monthly payment. A smaller monthly payment over a longer term often costs far more in total interest.
Skimming the lease agreement. Fair market value residuals and balloon terms can surprise you at the end; read the fine print.
Overextending before a slow season. Don't stack new payments right before your quietest months.
Missing the Section 179 window. The equipment has to be in service by year-end to deduct it this year.
Equip Your Restaurant for Success
The right financing gets you the equipment you need while protecting your cash flow, and for most established restaurants, that means buying with a loan and taking the Section 179 deduction, or leasing when you'd rather stay flexible. Compare the true cost, match the financing to the purchase, and keep your reserves intact.
When you're ready to finance your next oven, walk-in, or full kitchen, apply today to see what your restaurant financing options look like.
Frequently Asked Questions
Here are the questions I hear most from restaurant operators trying to finance equipment.
What Are the Financing Options for Restaurant Equipment?
The main options are an equipment loan, equipment leasing, an SBA loan, a business line of credit, a short-term loan, and vendor or dealer financing. Which fits depends on the cost, how fast you need it, and whether you want to own the equipment.
Is It Better To Lease or Buy Restaurant Equipment?
Buy long-life gear you'll keep for years, since you own it and can deduct the full cost with Section 179. Lease fast-changing equipment you'll upgrade soon or when you want to protect cash flow. Run your numbers through the calculator above.
How Long Does Restaurant Equipment Financing Take?
Online and specialized equipment lenders can fund in one to five days. A business line of credit can move even faster, while an SBA loan usually takes 30 to 90 days.
How Hard Is It To Get Restaurant Equipment Financing?
It's easier than most operators expect, especially for an established restaurant. Because the equipment serves as collateral, approval odds are higher than for an unsecured loan, even with less-than-perfect credit.
What Credit Score Do I Need To Finance Restaurant Equipment?
Specialized equipment lenders and leasing companies often approve scores in the 600s, while banks and SBA loans want higher. A stronger credit score and steady annual revenue earn you a lower rate.
Can I Finance Used Restaurant Equipment?
Yes. Many lenders finance used equipment, though terms may be shorter since the gear has a shorter remaining life. Inspect used equipment carefully, because it's also the collateral.
Is Restaurant Equipment Financing Tax Deductible?
Yes. Interest on an equipment loan is deductible, and Section 179 lets you deduct the full purchase price of financed equipment in the year you put it in service. Lease payments are deductible as an operating expense.
Michael Baynes
Co-founder, Clarify
Michael has over 15 years of experience in the business finance industry working directly with entrepreneurs. He co-founded Clarify Capital with the mission to cut through the noise in the finance industry by providing fast funding and clear answers. He holds dual degrees in Accounting and Finance from the Kelley School of Business at Indiana University. More about the Clarify team →
Related Posts