Low-interest business loans

Compare Low-Interest Business Loans

Compare 2026 low-interest business loan rates by loan type and credit score. See APRs for SBA loans, term loans, lines of credit, and more.

  • APRs starting at 6%
  • Loan amounts up to $5M
  • Credit scores from 500
  • Decisions as fast as same day
See Loan Options
Won't impact your credit
Michael Baynes
Written by
Michael Baynes
Bryan Gerson
Edited by
Bryan Gerson
Compare Low-Interest Business Loans

Rated 5 Stars on Google

Business owners trust Clarify because offer the lowest rates and fast approval.

Bad credit okay

Get approved with any FICO score. Our online application takes only a few minutes to complete.

Funding advisors

Let your Clarify advisor handle all the paperwork and get you best loan offers from lenders.

In my more-than-15 years of connecting entrepreneurs to the capital they need to grow, I'm always asked the same question: What's the best method of finding a loan at a low interest rate? And what credit score do I need to qualify?

The good news is that rates in 2026 are competitive. Below, I break down what low interest rates mean, how to qualify for the best ones, and seven ways to remove points from your APR before you even submit an application.

Type of loanBeginning APR (as of July 2026)Minimum credit scoreMaximum loan amountBest uses
SBA 7(a) loansBegin at 6.75%640$5MLong-term financing needs. Best for strong borrowers who are willing to wait weeks or months to close
SBA 504 loansBegin at 6.75%640$5.5MCommercial real estate and major equipment loans
SBA Microloans8% to 13%Varies by lender$50,000Startups and very small businesses, or working capital
Bank term loansVaries680+Varies by bankStrong financial history and established businesses, good credit
Credit union business loansVaries by credit unionEach credit union sets its own requirementsVariesCredit unions that provide business-friendly services to their members
Business lines of creditStart at 6%600$10K to $5MWorking capital and seasonal swings, recurring cash flow
Online short-term business loansStart at 6%550$10K to $5MSame-day funding, time-sensitive needs
Equipment loansStart at 6%550Up to 100% of equipment valuePurchasing equipment, vehicles, or machinery
Invoice factoring0.5% to 5% per invoice monthlyCustomer's credit scoreUp to 100% of invoice valueBusiness-to-business (B2B) companies with slow-paying customers

Comparing Low-Rate Business Loans

A low-interest business loan is almost always cheaper than other sources of financing. The average small business bank loan rate ranges from 6.37% to 10.98% at traditional banks.

Lenders reserve their lowest interest rates for the most qualified borrowers (borrowers with good credit, several years of history, and consistent annual revenue).

Every entrepreneur is unique. The best loan for an SMB will depend on how quickly you need the funds, how you plan to use them, and your current credit score. Here are some of the best small business loans with low interest rates I see borrowers choosing.

SBA Loans

SBA loans represent the lowest-cost financing option for most small to midsize businesses (SMBs). The Small Business Administration does not directly make loans; instead, it acts as a guarantor for portions of loans made by banks, credit unions, or non-bank lenders. When the SBA provides this guarantee, it reduces the lender's risk. This also results in lower interest rates for you. Of the SBA loan options, there are three that apply to the majority of small and midsize business owners.

  • SBA 7(a) loan. You can borrow up to $5 million with an SBA 7(a) loan. They allow for either working-capital or real-estate related expenses with repayment periods extending from 10 years to 25 years.

  • SBA 504 loan. These loans enable the purchase of commercial property or the acquisition of major equipment. The maximum amount allowed is $5.5 million. The repayment terms include 10-, 20-, and 25-year options.

  • SBA Microloan. This loan option is designed specifically for new ventures and/or extremely small companies. The maximum allowable amount is $50,000. The repayment period extends for seven years. Additionally, the interest rates associated with SBA Microloans usually range from 8% to 13%.

While SBA loans are a viable source of financing for most small to midsize businesses, they are generally slower than other options. The process for securing an SBA loan may require weeks to complete and involves providing tax returns, financial documentation, and a detailed business plan. Our SBA loans begin at 6.75% APR and extend to $5 million in principal.

Bank Term Loans

A bank term loan gives you a lump sum at a predetermined rate with fixed monthly repayments and a specific term. If you have solid financials and time to spare, pursuing a bank term loan may be worthwhile. If your credit is poor or you need immediate access to capital, an online lender or broker might be a better choice.

Credit Union Business Loans

Credit unions also offer competitive rates because they are non-profit organizations and distribute their profits back to their members. To get access to a credit union loan, you need to already be a member. But remember, not all credit unions engage in commercial lending activities. Each credit union establishes its own standards relative to interest rates, minimum credit requirements, and maximum loan amounts.

Business Lines of Credit

A revolving business line of credit functions similarly to a home equity line of credit or a credit card. You borrow what you need, only pay interest on the borrowed amount, and then replenish your credit limit upon repayment. Lines of credit are good options when you anticipate irregular or recurring expenses (inventory fluctuations, payroll between contract completion and commencement) where a single lump sum wouldn't suffice.

Clarify offers business lines of credit ranging from $10,000 to $5 million with an APR beginning at 6%, and terms ranging from six months to three years. To qualify, you need a minimum monthly revenue of $10,000, a minimum FICO credit score of 600, and at least 12 months of operational history.

Short-Term Business Loans

A short-term business loan is a single advance amount with repayment terms typically spanning six to 36 months. Speed and flexibility are the hallmarks of short-term loans. Banks rarely offer short-term financing. For these loans, borrowers often turn to online lenders like Clarify Capital. Online lenders provide quick access to financing and more flexible credit terms.

Clarify Capital's short-term loans offer APRs as low as 6%, principal ranges from $10,000 to $5 million, and approval for FICO scores as low as 550. We require a minimum monthly revenue of $10,000 and at least six months of operational experience. No prepayment penalty applies to our short-term loans.

Equipment Financing

Equipment financing uses the purchased equipment as collateral, reducing lender risk and resulting in lower interest rates than an unsecured loan. The typical repayment term for equipment financing corresponds with the expected useful lifespan of the equipment.

Equipment financing through Clarify offers financing equal to 100% of equipment value, with APRs as low as 6%, terms ranging from 12 months to 72 months, and a minimum FICO score of 550. Construction companies, trucking fleets, manufacturers, and medical practices commonly use equipment financing.

Invoice Factoring

If you operate a B2B business experiencing extended delays in receiving payment from customers, invoice factoring lets you convert those outstanding accounts receivable into immediate cash. You essentially sell the invoice to a factor at a minimal discount. The factor immediately advances most of the value of the invoice to you and subsequently collects from your customers. Your own FICO score plays virtually no role in qualifying for invoice factoring since the factor evaluates your customers' credit scores rather than yours.

Clarify Capital factors invoices up to one 100% of their face value, at fees ranging from 0.5% to 5% per invoice per month. For most small and medium businesses, invoice factoring serves as a cash-flow bridge until your company secures more conventional forms of financing.
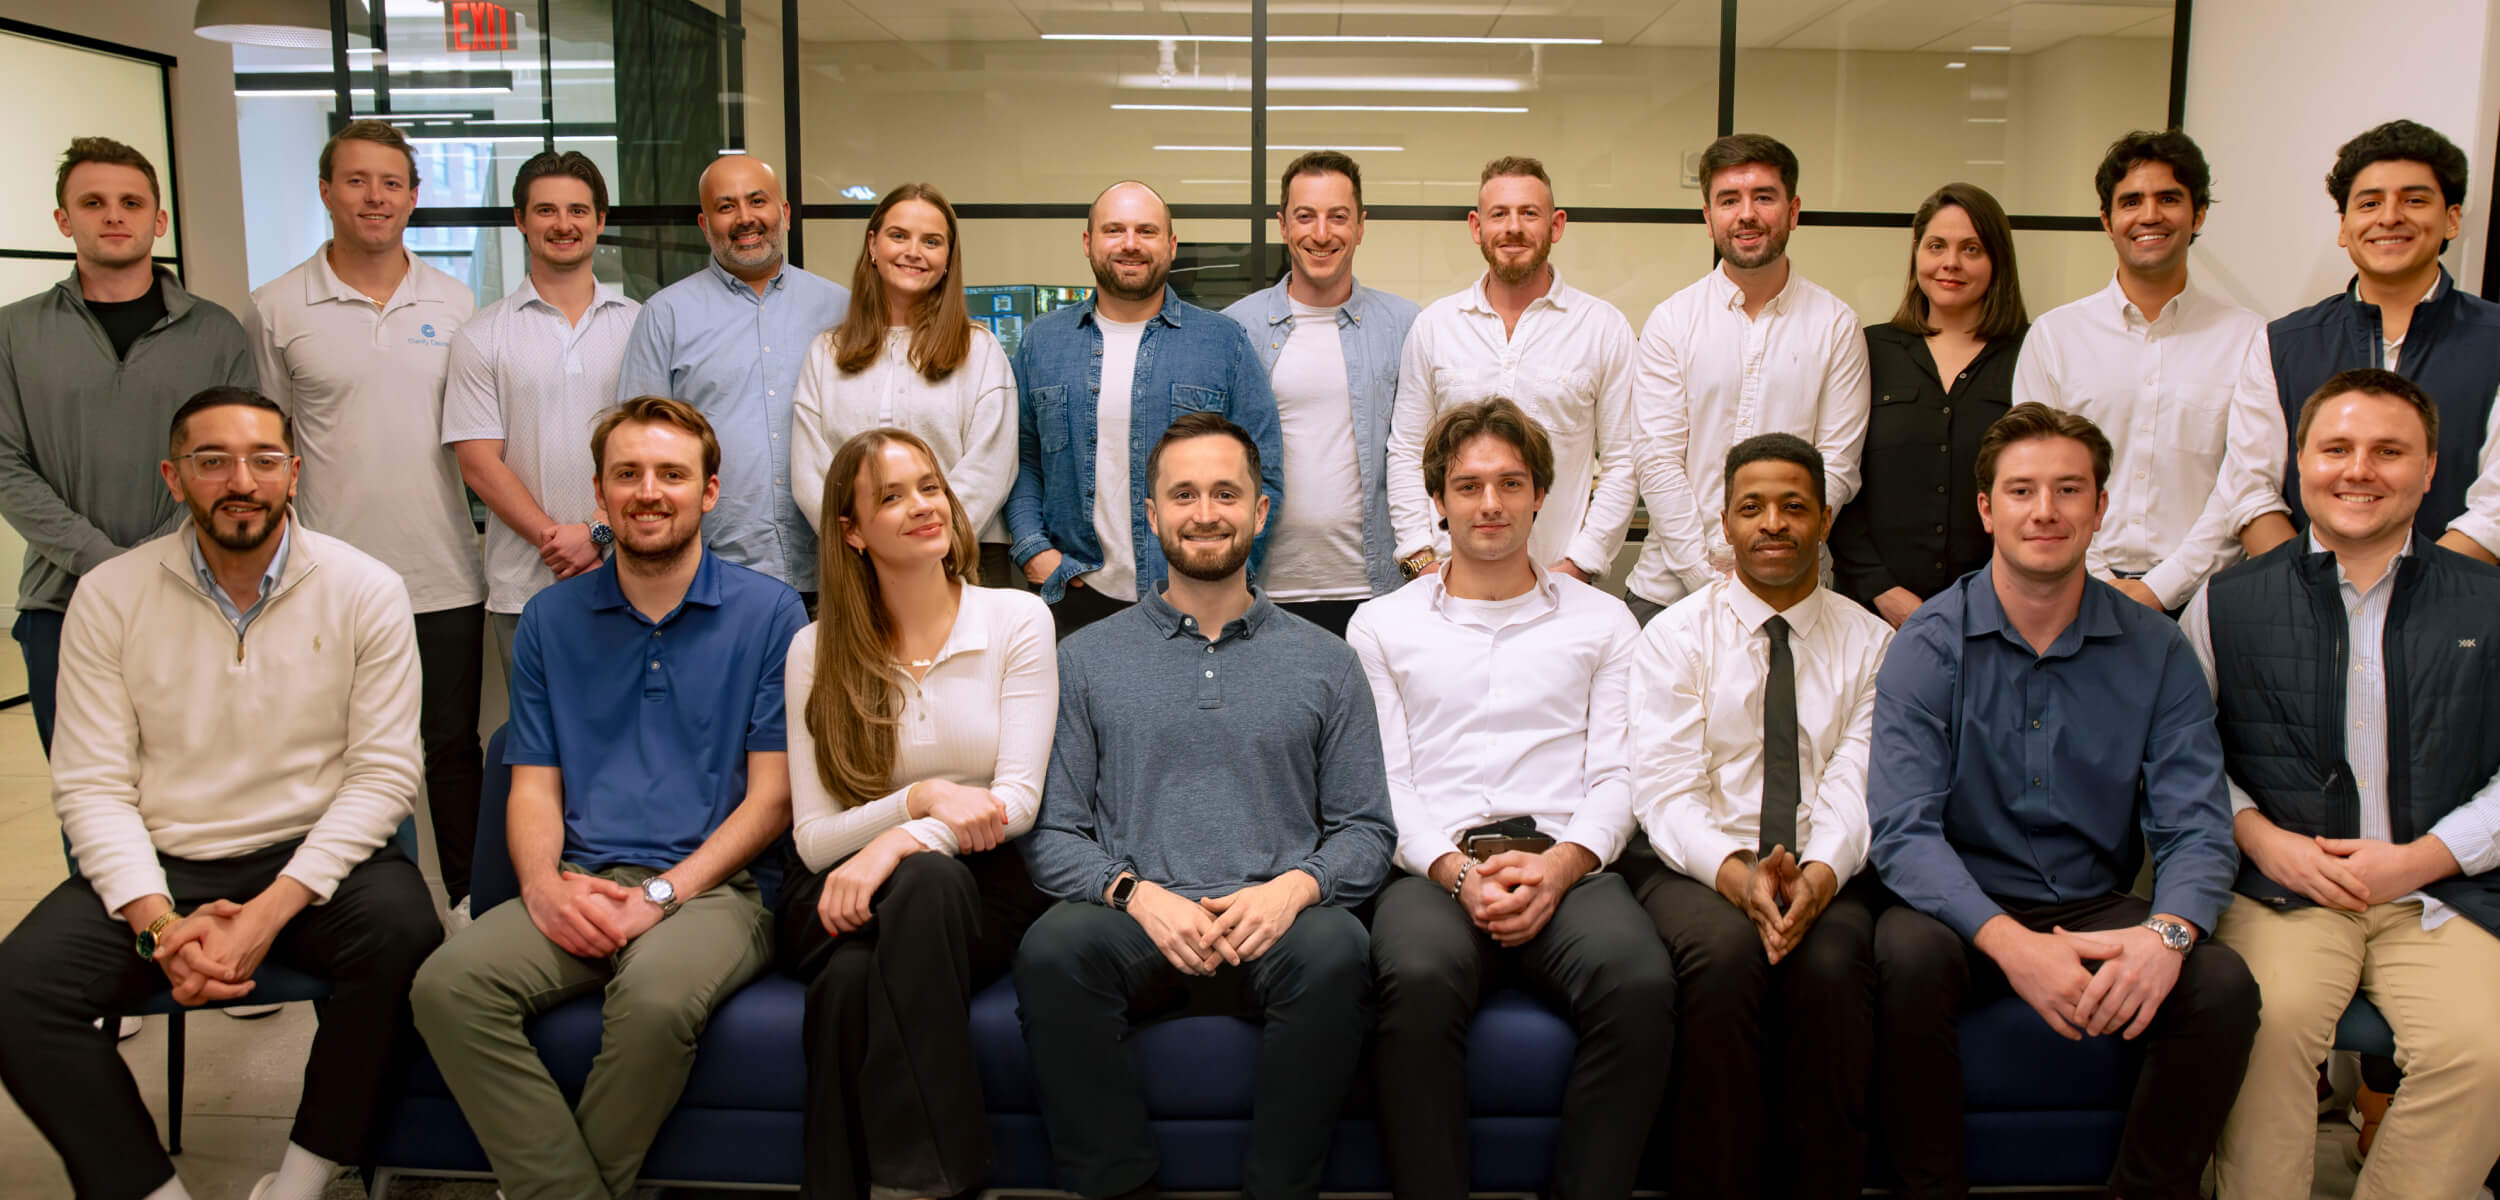
Meet your Clarify advisors

Clarify Capital low-interest business loan advisors

We make sure you get the lowest rate on your business loan, and set your company up for success. See how it works →

$

Minimum Requirements

Here are the basic requirements to qualify for a fast business loan. Even if you have bad credit, your Clarify advisor will guide you through it.

Monthly revenue

Over $10,000 in monthly revenue

Your business should bring in $10K or more in its bank account every month.

Credit score

Over 500 credit score

Any credit score works with us. Higher scores might get you better interest rates from lenders.

Time in business

Been in business for over 6 months

If your business has been running for at least 6 months, it's a good sign for lenders that you won't default on the loan.

Business bank account

Business bank account needed

Clarify will need the last three months of your bank statements to verify that your income is over $10K/month.

Start Application

Small Businesses ❤️ Clarify

Key Factors That Influence the Interest Rate on Your Business Loan

In addition to your credit score and revenue, there are four key factors that influence the final interest rate on your business loan.

Repayment term

Repayment term

Typically shorter repayment terms have lower APRs because the lender has less time for something to go wrong. Longer repayment terms cost more; however, the smaller monthly payment may fit your cash flow better even though you pay more in interest over time.

Collateral

Collateral

Business loans backed by real estate or equipment are priced at a lower rate than unsecured business loans because if you default the lender can recover their loss from the collateral. Examples of these types of loans include an SBA 504 and equipment loans.

Type of loan

Type of loan

Revolving credit such as lines of cre dit and business credit cards costs more than term debt since the lender doesn't know how much you will borrow. Term loans cost less because once the schedule is established it can't change.

Interest rate environment

Interest rate environment

Variable interest rates move with changes in the prime rate. As of July 2026, prime is at 6.75%. So if the Fed cuts again later in the year, variable APRs will follow.

Fixed vs. Variable Interest Rates

One of the most common questions that I get from customers is what the difference is between a fixed and a variable interest rate.

Fixed-rate loans have an interest rate that remains constant for the life of the loan. This makes budgeting easier and protects you when interest rates increase. Variable-rate loans vary based on a benchmark, such as the prime rate, so your payments decrease when interest rates fall but increase when they rise.

Here are some more key differences.

ElementFixed-rate loansVariable-rate loans
Stability of the rateThe rate remains the same for the entire length of the loanThe rate varies based on the direction of the market
Predictability of paymentFixed payments make it simpler to create a budgetPayments vary during the course of the loan
Protection when interest rates increaseProtects you when interest rates riseNo protection. Payments could increase
Savings when interest rates dropLimited savings option. You would need to refinanceSave money directly through reduced payments
Typical starting rateTypically higher than variableTypically lower than fixed

Alternatives to Low-Interest Business Loans

We offer a range of funding solutions for business owners. Our loan experts will walk you through each one.

$

You deserve low rates and an honest lender who has your back.

From our humble beginnings in 2018, we remain committed to helping American businesses get low-rate funding. We keep things simple, convenient and transparent. Read our manifesto →

How to get a low-interest business loan

How to Lower Your Business Loan Rate

There are seven methods that continually produce lower rates:

Raise your credit score before applying

Raise your credit score before applying

Reduce balances on existing debts, dispute errors on reports filed with credit bureaus, and request increases to your authorized spending limits, all of which can potentially raise you into a better pricing tier.

Provide collateral

Provide collateral

Securing a loan using tangible assets owned by your business (real estate, equipment) increases the lender's recovery potential should you default on the loan. This historically lowers your interest rate.

Reduce the length of the loan term

Reduce the length of the loan term

Borrowers who repay loans over shorter terms normally receive lower APRs due to fewer months for issues related to repayment to arise. Longer terms may result in higher interest rates yet generate more manageable monthly payments that may work better with your business's cash flow.

Increase the down payment

Increase the down payment

Larger initial down payments reduce lender risk and result in lower rates, especially with real-estate secured loans and equipment financing.

Show steady revenue growth

Show steady revenue growth

Many lenders review your past 3 to 12 months' bank statements when evaluating your ability to repay a loan. Consistent growth in income opens up more attractive loan options.

Compare multiple lenders

Compare multiple lenders

APRs vary widely among lenders offering identical loans. Due to this variability, comparing multiple lenders is necessary.

Refinance once your credit improves

Refinance once your credit improves

If you take advantage of a short-term loan at a higher rate due to an urgent need for capital, consider refinancing into a longer-term loan with a lower APR after 6 to 12 months, once your credit profile has improved.

Explore Low-Interest Loan Options Today

Ready to explore low-interest loan options? With Clarify Capital, you can compare your financing options across our network of 75+ lenders.

Apply today to see what you qualify for. Checking your options won't impact your credit.

FAQs About Low-Interest Business Loans

These are some of the most common questions I hear from SMBs about low-interest loans.

What Does Low-Interest Mean for a Small-Business Loan?

A low-interest business loan typically has a rate of 8% or lower. Only the top tier of applicants qualify for these types of rates. Right now, the prime rate is sitting at 6.75%.

Which Big Bank Is the Best Choice for a Low-Interest Business Loan?

That depends on a number of factors. National banks provide competitive pricing on SBA loans and lines of credit for those with a minimum credit score of 620. Community banks and credit unions can offer better rates within their specific market areas. Online SBA lenders also do the paperwork faster than most local banks. A solid approach is to get quotes from three to five different lenders, or work with a loan broker that can pull all the quotes at once.

How Much Is My Monthly Payment Going To Be on a $50,000 Small-Business Loan?

This also depends on the rate and how long you want to borrow it for. At 8% for five years, your monthly payment would be approximately $1,014 per month. At 10% for five years, your monthly payment would be around $1,062. If we were to take the same loan out for three years instead of five years at a 12% interest rate, your monthly payment would increase dramatically to $1,661 per month because the shorter term creates more pressure on the repayment schedule. Most lenders will perform the calculations for you in each quote.

How Difficult Is It To Get a $1 Million Small-Business Loan?

Most lenders require strong fundamentals such as a minimum credit score of 680, two or more years of operating history, $1 million in annual gross sales or revenue, clean financials, and collateral. For larger loans, you should anticipate a longer underwriting process, including submission of prior-year tax returns, profit and loss statements, and debt schedules.

How Does APR Differ From Interest Rate?

The interest rate is simply the percentage paid by the borrower to the lender based on the principal borrowed. APR takes into consideration the origination fee charged by the lender along with other recurring costs associated with the loan, and adds it to the interest rate. If you were borrowing $100,000 at 6% interest over three years with an origination fee of 3%, your APR could potentially be close to 8%. Always review APRs when comparing multiple loan options.

What Are the Major Differences Between Fixed vs. Variable Interest Rates?

Fixed rates remain constant throughout the entire duration of the loan, so your monthly payment remains constant. Variable rates fluctuate with changes to various indexes or prime rates, so your monthly payment increases when interest rates rise and decreases when interest rates decline.

Is My Information Secure When I Submit an Application to Clarify Capital?

Clarify follows SOC 2 security principles. A lending advisor can discuss any questions regarding Clarify's handling of applications prior to submitting any application material.

Types of businesses we fund

Clarify provides low-interest loans to businesses in all types of industries. Here's a few of them:


Apply for low-interest business loan

Ready for a low-interest business loan?

Get quick approval and APRs as low as 6%. Flexible repayment options are available for credit scores over 600.

$