Working capital loans

Working Capital Loans: Borrow up to $5M

Compare working capital loans by speed, rate, and term, plus what lenders check and what each type really costs.

  • Borrow from $10,000 up to $5,000,000
  • APRs starting at 6%
  • Financing as fast as same day
  • Terms from 6 to 36 months
  • No collateral required
  • Weekly, biweekly, or monthly payments
See Loan Options
Won't impact your credit
Bryan Gerson
Written by
Bryan Gerson
Working Capital Loans: Borrow up to $5M

Rated 5 Stars on Google

Small business owners love Clarify because get them the lowest rates possible on their loan.

Easy approval process

Find the best working capital loan online with our simple online application.

Dedicated lending experts

Your Clarify advisor does all the legwork for you and gets you funded the same day.

Working capital loans fill the gaps that come up in the day-to-day when running your business. They can cover payroll, rent, inventory, and utilities.

I've spent years arranging financing for small to midsize business owners. The ones who handle the ups and downs the best are the ones who use business financing to cover cash-flow gaps.

Below, I cover how the different types of financing compare, what lenders review, and what it costs.

Financing typeFunding speedTypical termTypical rateCollateralBest for
Business line of creditAs fast as same day6 to 36 months, revolvingAPR starting at 6%Not requiredRecurring or unpredictable gaps
Short-term business loanAs fast as same day6 to 36 monthsAPR starting at 6%Not requiredA known, one-time expense
Merchant cash advanceAs quickly as same dayNo fixed term, based on monthly salesFactor rate 1.08 to 1.45Not requiredCard-heavy sales, weaker credit
Invoice factoring1 to 2 weeksTied to when your customer pays, typically 30, 60, or 90 days0.5% to 5% per invoice per monthThe invoice serves as the assetSlow-paying business customers
SBA loanAs fast as two weeks, typically 30 to 90 days10 to 25 yearsAPR starting at 6.75%Sometimes required, depending on loan size and programLowest cost when you can wait
Home equity line of creditAs fast as one weekUp to 30 years, five-year drawAPR as low as primeQualifying real estate, 1 to 4 unitsHome equity and a longer payoff

Types of Working Capital Financing

Each type of working capital financing solves a different problem for your business. See how they compare against your own cash flow.

Business line of credit

A revolving credit line you draw from as needed. You only pay interest on what you use. Terms run 6 to 36 months

Short-term business loan

You get the money as a lump sum. Repayment happens on a fixed schedule, and terms run from 6 to 36 months.

Merchant cash advance

A company advances cash against your future sales. It takes a cut of the revenue until it's repaid. Lenders price at a factor rate of 1.08 to 1.45 instead of an APR.

Invoice factoring

A factoring company turns your unpaid invoices into cash by advancing up to 100% of the value against your accounts receivable. Then they collect from your customer. Fees are 0.5% to 5% per invoice per month.

SBA loan

The U.S. Small Business Administration (SBA) guarantees part of the loan, which makes this a cheaper option. Terms run 10 to 25 years. Financing can land as fast as two weeks, but typically takes 30 to 90 days.

Home equity line of credit

A revolving line of credit secured by your house. Another cheap option since the rate is anchored to prime. The trade-off is that if you can't repay the line, your home could be at risk.

What Lenders Consider

Working capital loans can be used to cover anything that you use to run your business: payroll, rent, utilities, inventory, supplier invoices, repairs, advertising, and the other everyday expenses that keep the lights on.

Here's what lenders review when considering you for a working capital loan.
Time in business

Time in business

Clarify Capital asks for at least six months of operating history. SBA lenders typically look for two years of operating history before they'll consider you for a loan.
Revenue

Revenue

Lenders want to see consistent, strong monthly revenue. Clarify Capital looks for at least $10,000 a month.
Personal credit score

Personal credit score

Better scores typically unlock better repayment terms and interest rates.
Cash flow

Cash flow

Lenders compare current assets against current liabilities. Lenders compare current assets against current liabilities to gauge liquidity and confirm you can absorb another payment.
Collateral or personal guarantee

Collateral or personal guarantee

Revenue-based financing asks for a personal guarantee. Other types of financing may ask you to pledge business assets.
Existing business debt

Existing business debt

Lenders review any advances, card balances, and open loans.
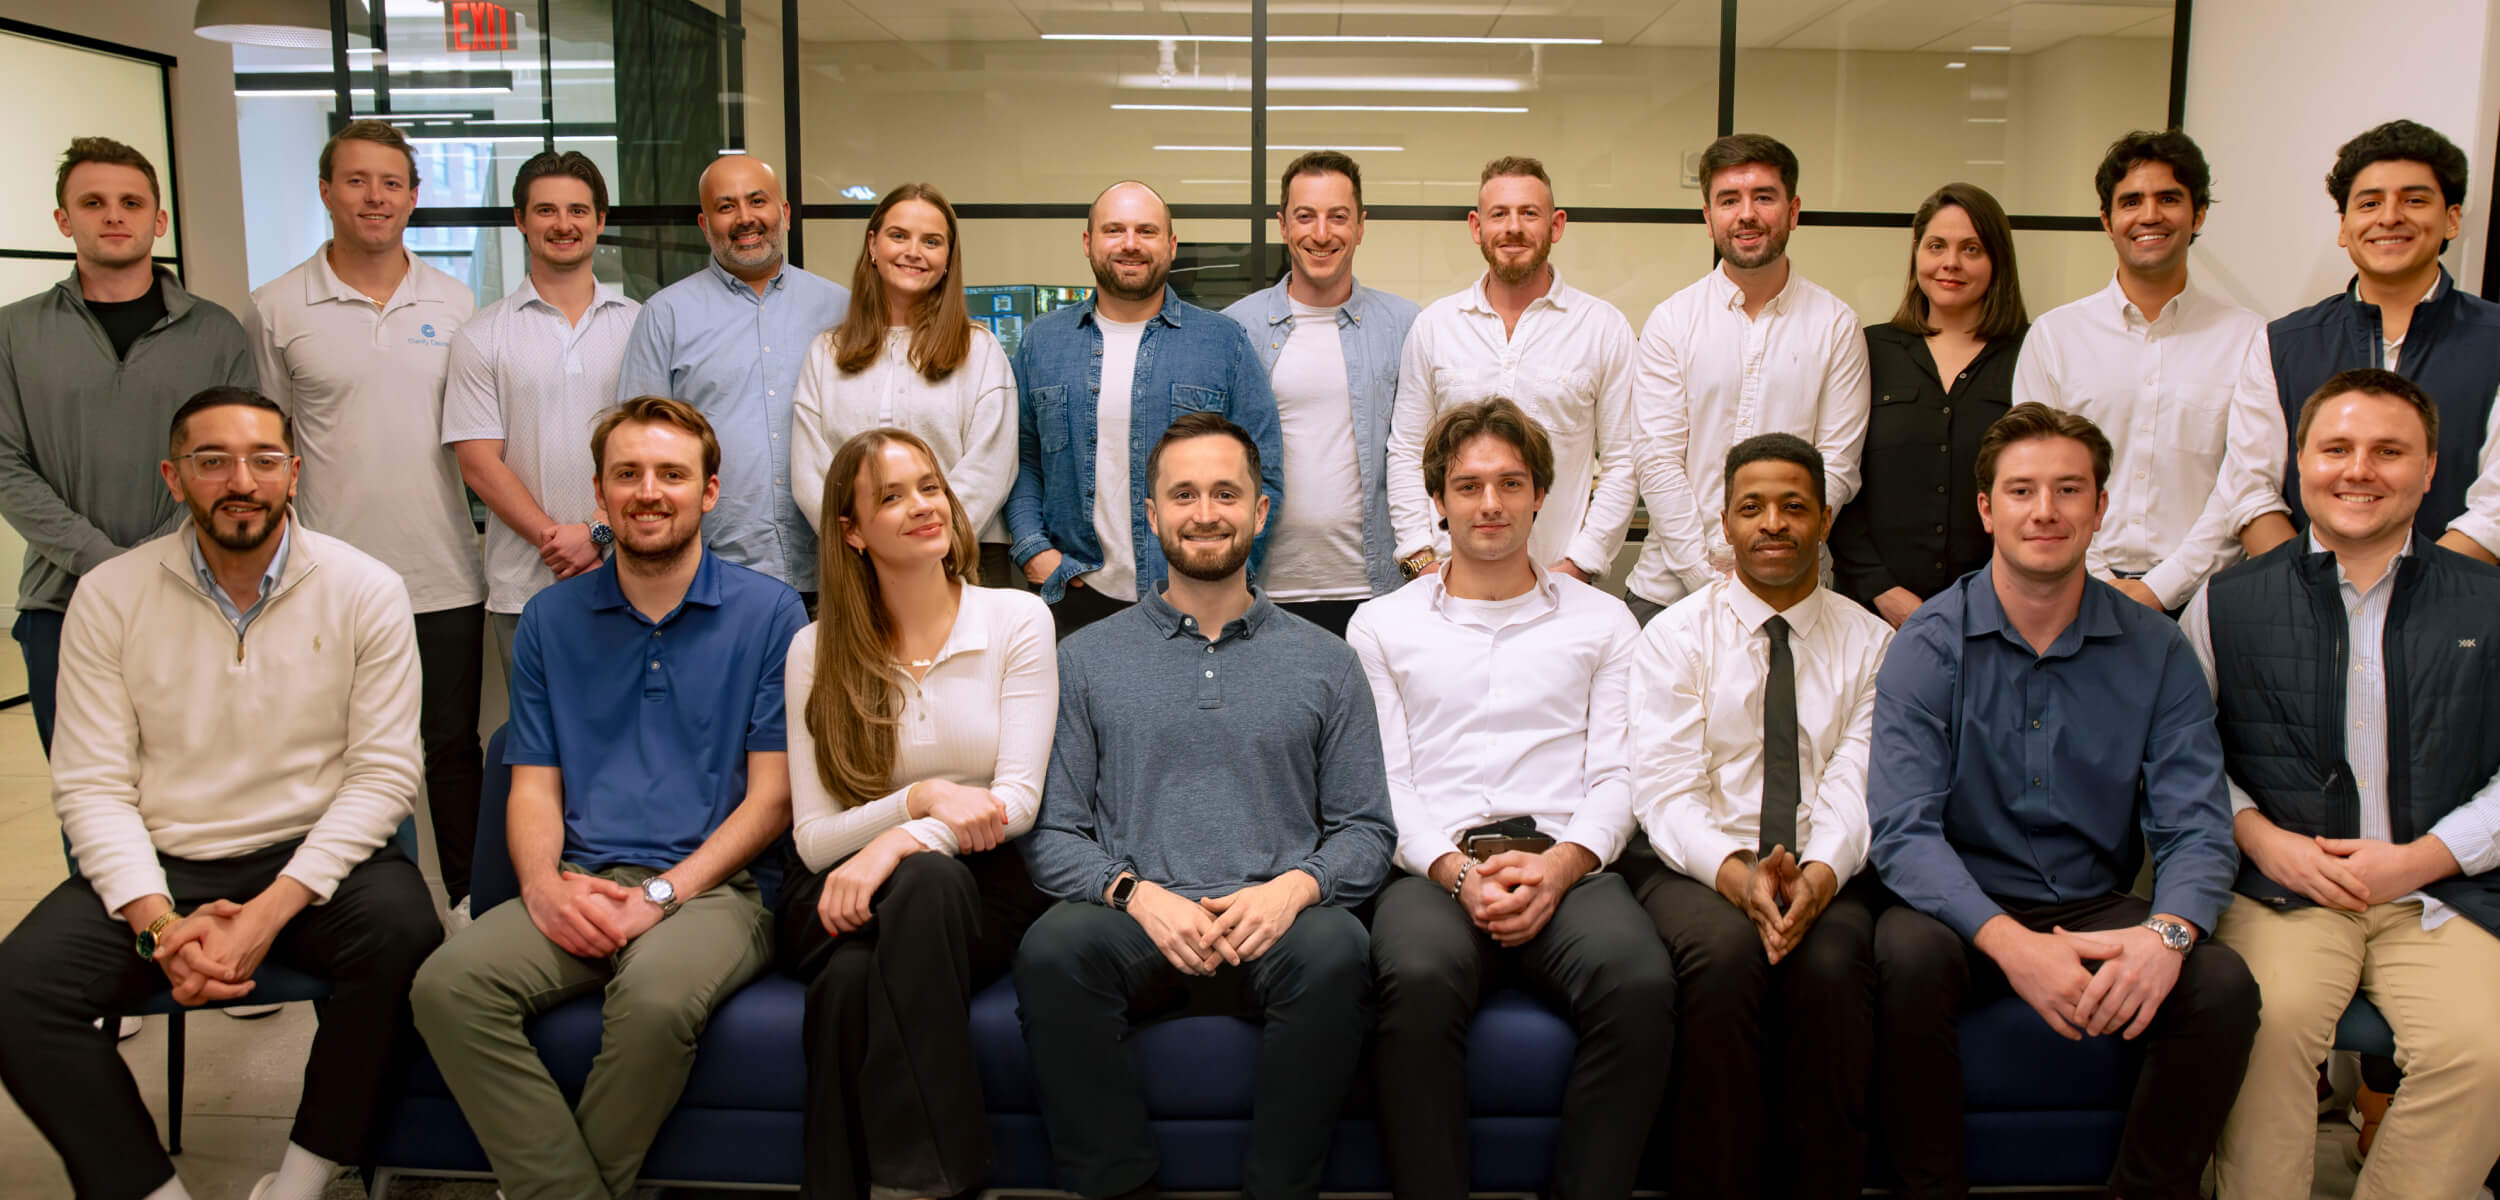
Meet your Clarify advisors

Clarify Capital working capital loan advisors

Your advisor will make sure you're getting the best working capital loan, and set your company up for success. See how it works →

$

Minimum Requirements To Qualify

Here is the minimum criteria to qualify for a working capital loan from Clarify. Your Clarify advisor will guide you through everything, even if you have bad credit.

Monthly revenue

At least $10K monthly revenue

Your company must be earning at least $10K per month in gross sales. At the moment we don't fund pre-revenue startups.

Credit score

Credit score above 500

Any credit rating above 500 is okay to qualify for a working capital loan. The higher the score, the better the payment terms you can secure.

Time in business

You've been in business for over 6 months

Your company should have been operational for at least six months. This shows us that your business is sustainable and will be able to pay back the loan.

Business bank account

You have a business bank account

Your Clarify advisor will need 3-4 months of most recent bank statements to verify income during the approval process. This is often the only documentation needed from your end.

Start Application

Small Businesses ❤️ Clarify

What Working Capital Financing Costs

The interest rate, or APR, is the cost that most borrowers are familiar with, but working capital financing comes with other costs as well.

Fees are another common place where borrowers see additional costs creep in. Origination fees, for example, often get charged at closing.

Factor rates also trip people up. A factor rate is a multiplier. So a $50,000 advance at a factor rate of 1.35 means you repay $67,500 total, regardless of how fast you pay it off.

Factoring fees stack by time. A 3% fee on a $50,000 invoice costs $1,500 for the first 30 days. If your customer takes 60 days, it increases to $3,000.

Short-term loans also cost more each month, though you may pay less overall. Let's check out the spread by looking at the cost of a $50,000 loan at 12% APR.

Term lengthMonthly paymentTotal interest
12 months$4,442$3,309
24 months$2,354$6,488
36 months$1,661$9,786

It all depends on what your cash flow can handle. The monthly payment on the 36-month loan is much lower than the 12-month one, though you end up paying more interest over the life of the loan.

Alternatives to a Working Capital Loan

A working capital loan doesn't always make sense. Here are three situations where you might want to reach for another type of financing.

  • You need to buy equipment. In this case, equipment financing usually costs less. The machinery serves as collateral.

  • Your costs are small and recurring. Consider a business credit card. They're revolving, they're fast, and many offer rewards. The downside is they're typically more expensive.

  • You need money without adding debt. Equity or partner financing are good options when you don't want to add debt. The trade-off is that you give up ownership.

Alternatives to Working Capital Loan

Here are other funding options we provide for financing business expenses. We'll guide you through all options when you apply online.

$

You deserve low rates and an honest lender who has your back.

From our humble beginnings in 2018, we remain committed to helping business owners get the working capital they need. We make funding simple, convenient and transparent. Read our manifesto →

How to get a working capital loan

Match the Financing to Your Cash Flow Needs

The right path for your business comes down to matching the financing to your needs. A recurring cash flow gap may call for a line of credit, while a one-time expense aligns with a short-term loan.

Clarify Capital compares terms across our network of 75+ vetted, reputable lenders. A lending advisor will go through the numbers with you. Apply today and see what your revenue supports.

Working Capital Loans FAQ

Here are the questions I hear most from small to midsize business owners.

Can You Get a Loan for Working Capital?

Yes, you can get loans to cover working capital, including short-term loans, lines of credit, merchant cash advances, and invoice factoring.

What Is a Working Capital Loan?

Working capital financing covers the cost of running your business day-to-day. This includes payroll, rent, inventory, and utilities. Working capital loans don't cover large long-term purchases.

What Credit Score Is Needed for a Working Capital Loan?

It depends on the type of working capital financing you're applying for. To qualify for a merchant cash advance with Clarify Capital, you need a credit score of 500. SBA loans have stricter requirements. Most lenders ask for a score of 640 or more.

What Can You Use a Working Capital Loan For?

Use it to cover operating costs like payroll, inventory, utilities, supplier payments, repairs, marketing, and seasonal downturns. You can also use a working capital loan for growth opportunities, like a bulk inventory buy. These aren't great options for buying real estate or long-life equipment.

How Is a Working Capital Loan Different From a Line of Credit?

A working capital loan gives you a lump sum that you pay back over a fixed period of time. A line of credit gives you a limit that you can draw against repeatedly.

Can You Get a Working Capital Loan With Bad Credit?

Yes, though your options may include higher interest rates and shorter terms. Revenue-based lenders weigh cash flow and time in business more heavily than credit score.

Is My Information Secure When I Apply?

Clarify follows SOC 2 security principles. Your bank statements and personal information stay inside that framework.

Types of businesses we fund

Clarify funds all types of small businesses. Here's just a few industries we finance every day:


Apply for working capital loan

Ready for a working capital loan?

Get approved and have money in your bank account within 1-2 days. Prequalify without affecting your credit! Application takes only two minutes.

$