 Reviewed by
I've been in the small business lending space for more than a decade, and one of the financing options I recommend a lot to small and midsize business (SMB) owners with less-than-stellar credit scores is a business line of credit.
It works like a revolving pool of money you can draw, repay, and redraw from as needed. Some of my clients are surprised to learn that, though their poor credit does limit their options, it doesn't completely close the door on getting this type of financing.
A business line of credit is great for business owners who need flexible cash for things like buying inventory or covering payroll gaps during the off-season. To get one with a lower credit score, you'll need to lean on strong revenue and cash flow.
Here I'm going to walk through how lenders assess you with bad credit, what borrowing with a line of credit can cost, and how to improve your odds of getting one. I'll also go over how to apply for a business line of credit through Clarify Capital and, if you aren't ready, some alternative options to consider.
| Cost structure | Rates | Repayment terms | Qualification focus | Best for | |
|---|---|---|---|---|---|
| Business line of credit | Revolving credit, where you can spend, pay, and re-borrow; only pay interest on what you use | APR starting at 6% | 6 to 36 months; weekly or monthly payments | Business revenue and cash flow, credit profile, time in business, and existing debt | Ongoing or recurring expenses like inventory, payroll gaps, and short-term working capital needs |
| HELOC for business | Revolving credit line backed by home equity; funds may be disbursed up front depending on lender structure | APR as low as the prime rate | Up to 30 years, with a draw period of up to 5 years; monthly payments | Available home equity, personal credit, income, and ability to repay | Business owners with sufficient home equity who want access to flexible capital and are comfortable putting their home at risk |
| Invoice factoring | Accounts receivable financing: advance + remainder, minus fees after collection | Fees of 0.5% to 5% per invoice per month | Ends when your customer pays the invoice, typically in 30, 60, or 90 days | Quality of eligible invoices and the creditworthiness of your customers, rather than your credit alone | B2B businesses with unpaid invoices that need cash before customers pay |
| Merchant cash advance | Lump sum advance; repaid via percentage of future sales | Factor rates of 1.08 to 1.45 | No fixed term; repayment length depends on your sales, with daily, weekly, or monthly payments | Recent revenue and sales volume, especially card or other receivables activity | Businesses with strong, consistent sales that need fast capital and can handle frequent repayment |
Can You Get a Business Line of Credit With Bad Credit?
Yes, it's absolutely possible to get a business line of credit if you have a lower credit score. It narrows your options and ability to negotiate better terms/rates, but it's possible.
If you're wondering exactly what scores count as “bad,” the reality is that there's no one definitive number that every single lender uses to define that. They all have their own individual standards. But as a guidepost, the Federal Reserve's Small Business Credit Survey considers a business high credit risk if the personal credit score used for financing is below 620.
The thing to be aware of is that weaker credit means you're likely to be offered a smaller credit limit at a higher cost and with a shorter repayment period or more frequent payments.
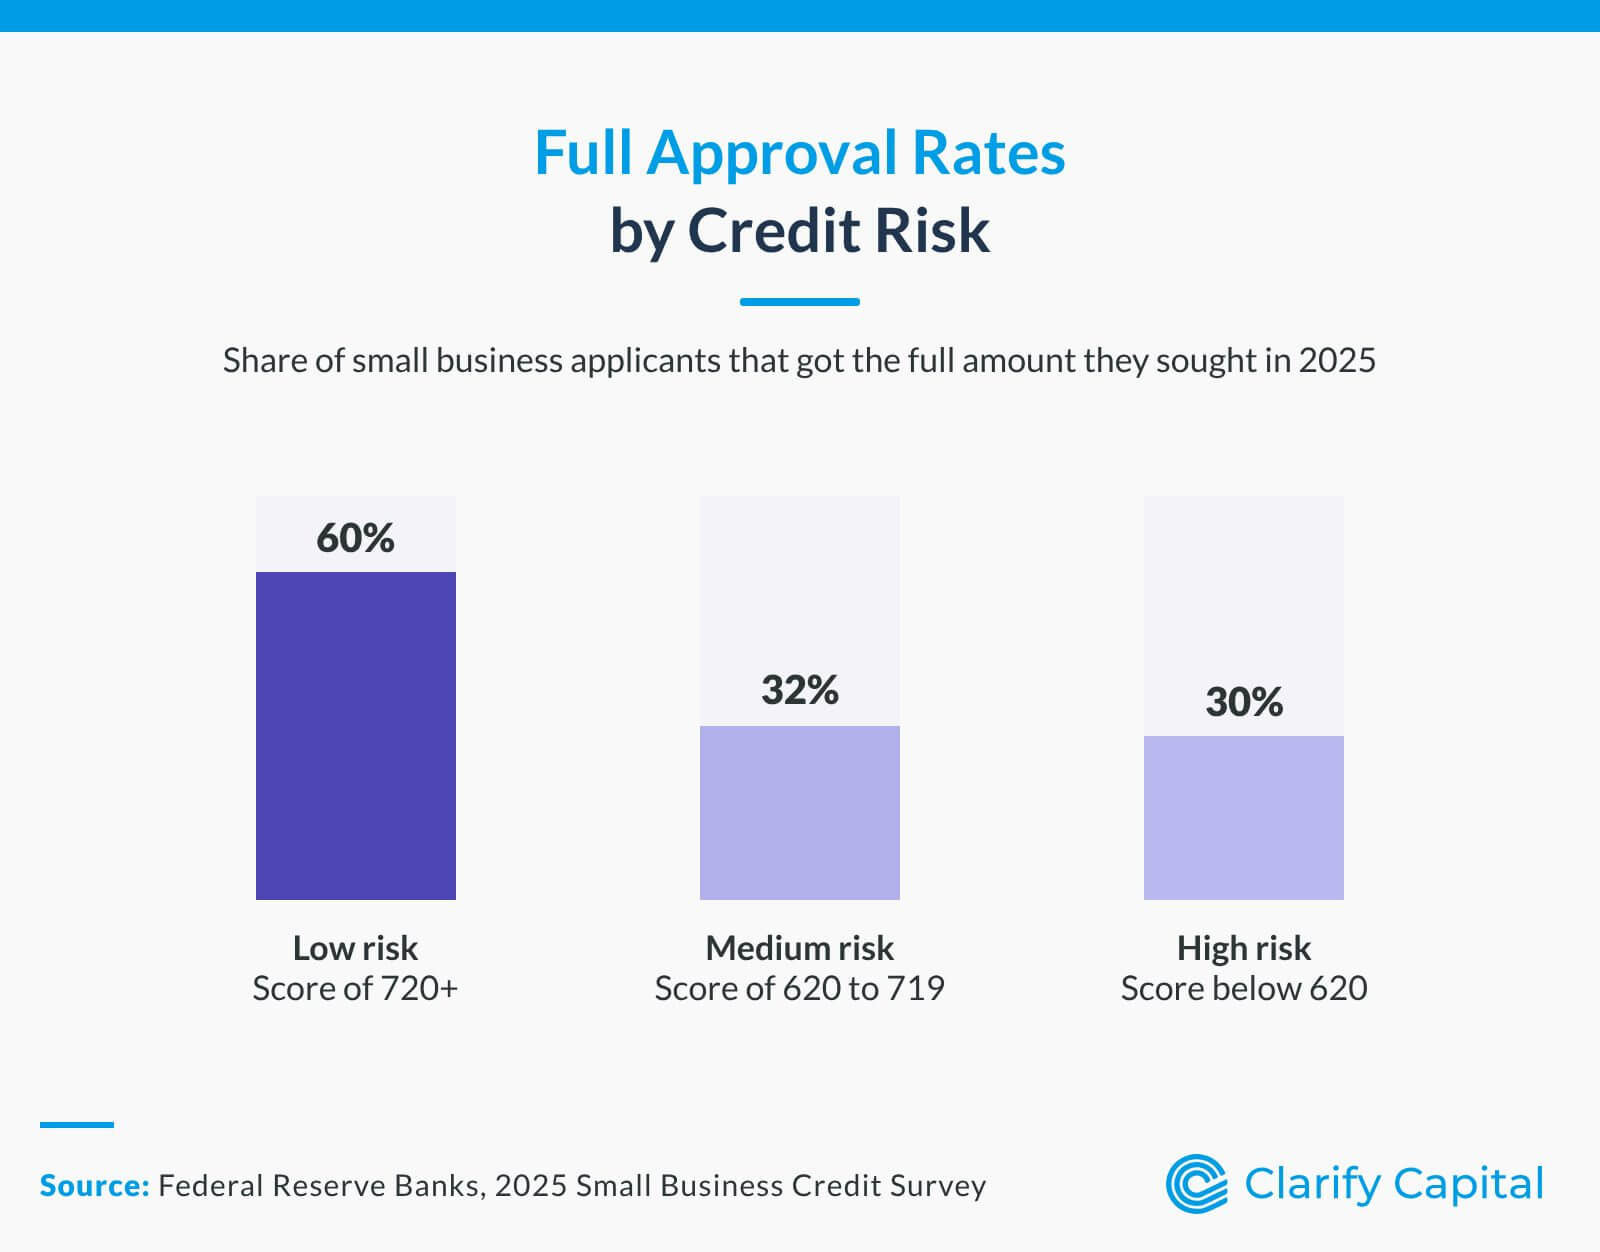
In addition to less favorable terms, it's important to be aware that low credit also often means you might not get as much as you want to borrow. In the Federal Reserve's 2025 Small Business Credit Survey, 60% of low-credit-risk applicants were fully approved for the financing they sought, compared with 32% of medium-risk applicants and 30% of high-risk applicants. (These figures cover applicants for loans, lines of credit, and merchant cash advances collectively, so they shouldn't be interpreted as approval rates for business lines of credit alone.)
What Lenders Look at Beyond Your Credit Score
If you have a lower credit score, there are other things lenders will weigh more prominently. Those can include annual revenue, cash flow, bank activity, time in business, industry, and available collateral.
The debt you already have, if any, can also matter a lot. If a lender thinks another debt payment could get in the way of your ability to repay a new line of credit, they might not give you an offer, even when other factors are working in your favor.
Secured vs. Unsecured Lines of Credit
As I just mentioned, your ability to put up some sort of collateral against the line of credit (whether business equipment, inventory, receivables, or, in some cases, a personal asset) can help your case with a lender. The logic for lenders is pretty simple: If you end up not being able to repay them, they have the power to potentially seize the asset to help them recover from their loss. This type of agreement would make it a secured line of credit.
Unsecured lines, which don't have a specific asset pledged in case of default, require stronger personal and business credit and may come with higher rates or lower limits because the lender has less protection.
| Secured line of credit | Unsecured line of credit |
|---|---|
| Requires collateral, such as equipment, inventory, receivables, or another eligible asset. | Doesn’t require a specific asset to be pledged as collateral. |
| May be easier to qualify for with weaker credit because the lender has something to recover if you default. | Usually puts more weight on your credit, revenue, cash flow, and business history. |
| May come with a higher credit limit or more favorable pricing. | May come with a lower limit or higher cost, especially if your credit is weaker. |
| Best for businesses that have assets they’re comfortable pledging. | Best for businesses that want to avoid pledging a specific asset and can meet stronger underwriting requirements. |
What a Business Line of Credit Can Cost With Bad Credit
Having a lower credit score will usually make any type of borrowing, including a business line of credit, more expensive. That higher cost comes because the lender is taking on a higher risk by lending to you. You might also be asked to put up collateral or a personal guarantee, as I mentioned earlier, which can be considered another cost in a different way.
The exact cost is always going to depend on the lender and the structure of the line of credit. Because there's no one “average” cost I can point out credibly, I'm going to break down a hypothetical example so you can still get an idea of what the cost could look like:
| Example cost | Amount |
|---|---|
| Amount drawn | $10,000 |
| Annual interest rate | 18% |
| Repayment period | 26 weeks |
| Estimated weekly payment | About $403 |
| Estimated interest paid | About $475 |
| 2% draw fee | $200 |
| $25 monthly maintenance fee for 6 months | $150 |
| Estimated total borrowing cost | About $825 |
As you can see here, a line of credit isn't just about the interest rate. It also tends to come with things like draw fees and maintenance fees, which here add $350. The frequent repayment schedules are another factor. In this example, because payments are weekly, the business would need to have roughly $403 available every seven days, which is a little over $1,700 a month.
All of those things affect what the financing actually ends up costing in total and how much pressure it puts on your business's cash flow.
How to Improve Your Chances of Approval
A low credit score doesn't have to stop you from applying for financing, but you might find that you'd rather wait until your financial profile is better to apply so you can get the best terms and rates possible.
When my clients make this choice, there are several things I tell them they can work on and do to improve their chances of approval for future loan or financing applications:
Review your credit reports
Check your personal and business credit reports for errors or outdated information, and dispute anything that's inaccurate before you apply.
Show consistent deposits
Steady deposits and healthy cash flow can help demonstrate that the business has enough money coming in to handle another payment obligation.
Pay down existing balances
Reducing outstanding debt can improve your overall financial picture and leave more cash flow available for payments on a new line.
Start with a smaller limit
Asking for only what you realistically need may make more sense than seeking the largest credit line available, particularly when your credit is weaker.
Avoid new credit problems
Stay current on existing accounts and avoid taking on unnecessary debt while you're preparing to apply.
Use the line responsibly
If you're approved, borrow only what the business needs and make payments on time. Responsible use can help strengthen your credit profile for future financing.
When a Line of Credit Isn't the Best Fit
In my opinion, a business line of credit is a good financing fit when you need flexible access to cash over time and would benefit from its revolving spend-repay-reborrow structure. But another financing or loan option might be better if you know exactly how much you need, want a larger lump sum, or have an asset or receivable that can support financing.
| Better for… | |
|---|---|
| Short-term loan | … a one-time expense, when you know how much you need up front and want a fixed repayment schedule instead of an open revolving line |
| Equipment financing | … when the money is specifically going toward equipment, because the equipment typically secures the financing, the structure may be more appropriate than using a general-purpose credit line |
| Invoice factoring | … businesses with unpaid B2B invoices that need cash sooner; instead of borrowing against a credit limit, you sell eligible receivables to a factoring company at a discount |
| Merchant cash advance | … businesses with strong card sales that need fast access to capital, but the cost can be high, and repayment can put pressure on daily or weekly cash flow |
At Clarify Capital, we can help you connect with lenders who offer all of these options. In fact, we've already helped more than 50,000 small and midsize businesses across 1,000+ industries get all kinds of financing. Here's what we require to work with us:
Minimum Qualifications
For Financing Through Clarify Capital

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
Sometimes, instead of any of these alternatives, the best move is to wait. If your credit has recently taken a hit, your cash flow is already stretched, or the only offers you get are going to strain your business, spending time paying down your existing balances and building a stronger financial profile (like the suggestions in the previous section) may put you in a better position to qualify for more favorable financing later on.
Why Small Businesses Work with Clarify Capital
I'll reiterate again that the right choice for your situation, whether a business line of credit, the alternatives I went over, or sitting tight while strengthening your profile, is always going to depend on you and your business.
At Clarify Capital, we have a 5.0 Trustpilot rating, the highest in the industry, and we pair every applicant with a dedicated U.S.-based lending advisor, rather than a chatbot or call center. If you were to work with us, here's what the process looks like:
Step 1:Apply online
It takes about two minutes. You'll need your business's legal name, EIN, time in business, monthly revenue, requested loan amount, owner contact information, and a credit authorization.
Step 2:Connect with a lending advisor
A U.S.-based Clarify Capital lending advisor reviews the application, runs a soft credit pull (no impact to your score), and requests 3 to 4 months of recent business bank statements.
Step 3:Get matched and funded
Clarify Capital works with 75+ vetted lenders and matches your profile with the right financing. Approvals often get a same-day offer (SBA loans can take longer).
If or when you're ready, my team and I can help you get started and compare options from our network of 75+ vetted lenders. Apply today.
Frequently Asked Questions
Can You Get a Business Line of Credit With Bad Credit?
Yes, you can, but you're likely going to get offers with less favorable terms and rates, as well as lower overall borrowing amounts. You might also be asked to put up collateral or make a personal guarantee.
Can I Get a Business Loan With a 500 Credit Score?
It may be possible, but a 500 credit score is very low by most small-business lending standards. For context, the Federal Reserve's Small Business Credit Survey classifies businesses using a personal credit score below 620 as high credit risk, so a score of 500 sits well below that. At that level, your options may be more limited and more expensive, and lenders may put greater weight on revenue, cash flow, time in business, and collateral.
What Is the Monthly Payment on a $50,000 Business Loan?
This will depend on the structure of the specific loan, the amount of the loan, the interest rate, and your repayment plan. As an example, if you borrowed $50,000 at 10% annual interest over five years, you can expect a monthly payment of approximately $1,062. A shorter term or a higher rate would increase the payment.
What Is the Easiest Business Line of Credit To Get?
If your credit is on the weaker side, a secured business line of credit is usually easier to get than an unsecured one. That's because it requires that there be an asset pledged as collateral, which gives lenders another layer of protection in the event you can't repay what you borrowed.
How Does Clarify Capital Protect My Business and Financial Information?
Clarify Capital follows System and Organization Controls 2 (SOC 2) security principles that protect sensitive business and financial information, including secure data handling practices, controlled access to information, and ongoing monitoring to help protect your data throughout the application and funding process.
Bryan Gerson
Co-founder, Clarify
Bryan has personally arranged over $900 million in funding for businesses across trucking, restaurants, retail, construction, and healthcare. Since graduating from the University of Arizona in 2011, Bryan has spent his entire career in alternative finance, helping business owners secure capital when traditional banks turn them away. He specializes in bad credit funding, no doc lending, invoice factoring, and working capital solutions. More about the Clarify team →
Related Posts