 Reviewed by
You were turned down by your bank. Maybe your credit is thin, or your business is in an area that scares banks.
I'm Bryan Gerson, co-founder of Clarify Capital. I've helped thousands of small and midsize business (SMB) owners who heard the "no" and got money anyway. Alternative business financing is any money you get for your business except for money financed through a traditional bank. It helps you get access to capital quickly and often has less strict requirements than traditional banks.
Below, I go over the six major alternative financing options, in order of least difficult to get to most difficult to get, show how to identify a quality lender versus a poor lender, and give you guidance on transitioning to a bank loan.
| Alternative option | Time to cash | Interest rate and fees | Best use |
|---|---|---|---|
| Line of credit | As fast as same day | APR starting at 6%, only charged on drawn amount | Recurring cash flow disruptions |
| Merchant cash advance | As fast as same day | Factor rates 1.08 to 1.45, very high | Fast cash, paid based upon card sales |
| Invoice financing | Days | Fee paid on advance | Borrowing against unpaid accounts receivable |
| Invoice factoring | One to two weeks to set up | 0.5% to 5% per invoice per month | Selling accounts receivable and taking collections off your plate |
| Equipment financing | One to five days | APR starting at 6%, secured by the equipment | Equipment purchases payable over their useful life |
| Home equity line of credit | About one week | As low as the prime rate | Owners with home equity whose business can't qualify yet |
What Is Alternative Financing?
Alternative financing is any type of money you use to finance your business that doesn't come from a traditional bank. Alternative financing sources include online lenders, private lenders, and lending marketplaces. These lenders look at the cash flow and revenue of your business as opposed to your credit history, and they can process applications much quicker.
When your bank says no, many SMBs use alternative financing as their next option.
Minimum Qualifications

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
Six Types of Alternative Financing, Ranked From Least to Most Difficult
Some alternatives are much easier to get than others. Here are six examples of common types of alternative financing, listed in approximately the order of ease to difficulty to obtain.
| Alternative option | How it works | What Clarify Capital requires |
|---|---|---|
| Revolving business line of credit | An open-ended line of credit allows you to borrow what you need as you need it, repay it, and borrow again. You only pay interest on the outstanding balance. It's the most flexible form of alternative financing available and works for recurring cash flow gaps that come up regularly. | A credit score of at least 600 and a year in operation. Rates begin at 6% APR. |
| Merchant cash advance | A merchant cash advance provides you with a single up-front lump sum of capital that you repay in proportion to your daily card sales. It's the fastest way to receive financing and the easiest form of alternative financing to qualify for. Merchant cash advances are very expensive, however. The factor rate can range from 1.08 to 1.45, and over a short repayment period, this can translate to a high effective APR. | A minimum credit score of 500. We can fund as fast as same day. |
| Invoice factoring | Invoice factoring represents an additional layer beyond invoice financing. Instead of simply borrowing against your accounts receivable, you sell them to an invoice factoring company for immediate cash, and they take responsibility for collection efforts. | Advances can run up to 100% of the value of the invoice, and factoring companies can charge anywhere from 0.5% to 5% per invoice per month. Setting up an arrangement takes one to two weeks, so it can't be used for emergency financing requirements. |
| Equipment financing | Equipment financing is limited to one specific item that you intend to purchase. The item purchased becomes collateral for the loan. | Since equipment financing is secured, we offer competitive rates beginning at 6% APR, and we require fewer qualifying criteria than an unsecured loan. Terms can extend from 12 to 72 months, matching the useful life of the equipment financed. |
| Home equity line of credit (HELOC) | A HELOC differs significantly from the other options. It's granted based upon you (the owner), not upon your business. Lenders review your personal income, your credit history, and how much equity exists in your home, meaning the value of your home less any outstanding mortgage balances. None of these factors relate to either your revenue or length of time in business. This distinction makes a HELOC one of the few financing options available to businesses that are either too young or experiencing slow periods financially. | A 620 credit score. Our lowest possible rates begin at the prime rate and our longest possible term extends to 30 years. We can fund as fast as one week. The risk is that if you default on repaying the HELOC, you stand to lose your home, a greater obligation than any of the unsecured options. |
Other methods can generate money for your business as well. Crowdfunding platforms and peer-to-peer lending allow you to generate cash by promoting your business opportunity and potentially giving away part of your equity. SBA Microloans are typically issued through nonprofit lenders and enable you to raise smaller amounts of money.
Alternative Financing Doesn't Always Mean Predatory Practices
While there are predatory practices associated with some forms of alternative financing, this isn't always representative of the entire category. The lender, rather than the category, is what matters when evaluating alternative financing. In a Federal Reserve survey, 60% of firms that used online lenders indicated that their borrowing costs exceeded expectations, which represented a larger percentage than any other type of lender.
Here's how you can tell the difference between a good lender and a predatory one.
Get the cost as an APR
Request the annual percentage rate (APR) rather than simply a factor rate or flat fee, so you can compare offers based on similar criteria.
Review all charges
Origination, servicing, and prepayment charges add up quickly. Review all charges prior to signing.
Understand the payment mechanics
Frequent daily or weekly debits may severely drain your operating cash flow. Review both the payment amount and frequency, as well as whether making an early payoff results in saving money.
Watch for pressure and vague pricing
If a lender rushes you to sign or avoids answering direct questions regarding pricing, it may indicate that they're trying to hide something.
Review the track record
Evaluate each lender based on their overall track record, including customer reviews, rating systems, and the number of years they've been providing financing.
Use a marketplace to compare offers
At Clarify, we compare multiple offers from 75+ vetted, reputable lenders, so you'll view actual terms side-by-side rather than relying solely upon one lender's representation.
Comparing Alternative Financing and Traditional Banking
Both traditional and alternative financing have benefits and drawbacks. Each method suits different times within a business owner's journey.
Traditional banking is designed for planned long-term investing at lower costs, while alternative financing trades higher costs for speed and access when you can't wait or can't qualify. Here's the difference in plain terms.
| Factor | Alternative financing | Traditional bank loan |
|---|---|---|
| Approval time | Hours to a few days | Weeks to months |
| Qualifying criteria | More flexible, weighs revenue and cash flow | Stricter, needs credit history and business experience |
| Cost | Higher interest rates and fees | Lower interest rates |
| Best for | Speed, flexibility, low credit score | Big, planned, lower-cost borrowing |
Transitioning From Alternative Financing to a Bank Loan
Alternative financing works best as a temporary measure until you establish enough credibility and liquidity to secure more favorable bank loan rates. Establish credibility by maintaining clean financial records and growing revenues consistently over a prolonged period, and reduce any existing debt obligations prior to seeking bank financing.
Build business credit
Pay every obligation on time and keep accounts in your business's name, so a credit file builds under the company rather than under you personally.
Establish credibility through clean financial records
Maintain clean financial records that accurately represent your business operations, past performance, and future outlook. Banks require consistent financial reporting, complete transparency, accurate accounting practices, and sufficient cash flow management prior to extending any financing.
Document consistent revenue growth
Consistently increasing revenue over multiple consecutive quarters shows an ability to manage increased levels of debt, which builds more confidence in your capacity to repay bank financing.
Eliminate existing debt obligations prior to seeking financing
Reduction in existing debt obligations creates a positive impression during your initial meeting with potential lenders, and helps reduce your likelihood of being declined for financing due to excessive debt obligations.
Select the Appropriate Type of Alternative Financing for Your Needs
Banks aren't always willing to say yes immediately after receiving an application. When this occurs, selecting the correct type of alternative financing can be an advantage for your business.
Clarify Capital gives small and midsize businesses the ability to compare multiple alternative financing options side-by-side, using our network of 75+ vetted, reputable lenders. You'll be matched with a U.S.-based lending advisor to assist you in making an educated decision about which type of alternative financing best meets your specific needs now.
When you're ready to compare offers, apply today. Checking your options will not affect your credit score.
FAQs About Alternative Financing
Here are straight answers to the most common questions I hear from clients about alternative financing.
What Are Examples of Alternative Financing?
Some examples include a business line of credit, a merchant cash advance, invoice financing, invoice factoring, equipment financing, a home equity line of credit (HELOC), a crowdfunding campaign, a peer-to-peer loan, an angel investor, and an SBA Microloan. What they have in common is that none of them comes from a traditional bank.
What Are the Easiest Alternative Financing Options To Qualify For?
A merchant cash advance and invoice financing are generally easier to qualify for, since the decision leans more on your sales than on your personal credit history. Instead, the underwriting will be based upon your daily, weekly, or monthly card sales, or your customers' invoices. A line of credit is also available for companies generating consistent revenue. If your credit score is on the low side, these revenue-based options are the ones most likely to work for you.
How Quickly Can I Get Cash With Alternative Financing?
A merchant cash advance, a line of credit, and a short-term loan can be funded as fast as same day. It takes anywhere from one to five days to get approved for equipment financing, and about a week for a HELOC. Invoice factoring takes one to two weeks to set up, and after that, advances move quickly. One reason many business owners opt for alternative lenders is their faster approval process compared to banks.
Are Interest Rates Higher for Alternative Financing?
Yes, usually. The quicker approval and less stringent requirements result in higher interest rates and fees. Make sure to compare offers on an annual percentage rate (APR) basis when determining the true cost. Consider the value of the speed and access against the increased costs of obtaining alternative financing.
How Much Is the Monthly Payment on a $50,000 Business Loan?
Assuming an APR of 6% over 24 months, the monthly payment is about $2,220, and the total amount paid is roughly $53,185, which works out to about $3,185 in total interest. Extending the repayment period to 36 months would reduce the monthly payment to approximately $1,520 but increase the total interest paid to roughly $4,760.
Alternative financing options will typically quote an APR greater than 6%, so make sure to calculate the estimated payment amounts using the terms quoted in your offer. Your Clarify lending advisor can show you specific payment scenarios based on your qualifications.
Can an LLC Get Grant Funding?
Many grant programs allow businesses operated through an LLC, as long as the business has a valid Employer Identification Number (EIN) and is registered with the Secretary of State's office. The challenge for business owners comes when identifying a legitimate source for grant funding. The SBA doesn't give grants for starting or growing a typical small business. Its grant money goes toward nonprofit organizations that serve as resource partners and educational institutions, and those organizations provide education and training to business owners.
State economic development agencies and local chambers of commerce, along with corporate funders, are good sources for potential grants. Federal opportunities can be found at Grants.gov. Grants are competitive and may take several months to award. That's why most business owners view grants more like icing on the cake than as part of their overall growth strategy.
Can Alternative Financing Improve My Business Credit Score?
Providing timely payment on loans is key to improving your business credit scores. In addition to making timely payments, consider selecting a lender that reports to the major business credit bureaus. Some alternative lenders report to the business credit reporting agencies, while others don't. If improving your business credit score is a goal of yours, ask whether this is something the lender provides prior to signing an agreement.
Does Alternative Financing Require Collateral?
Not all forms of alternative financing require collateral. Equipment financing is secured by the purchased equipment, factoring is secured by your outstanding accounts receivable, and a HELOC is secured by your primary residence. Lines of credit and advances are typically unsecured, although you may still have to provide a personal guarantee, which means you'll be personally liable should your company default on any obligations owed to the lender. Prior to executing any type of loan documents, make sure you understand exactly what you're pledging as collateral.
Is My Information Safe When I Apply?
Clarify follows SOC 2 security principles. If you have any questions regarding how we handle applications, please feel free to contact a lending advisor prior to sending us any documentation.
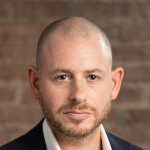
Bryan Gerson
Co-founder, Clarify
Bryan has personally arranged over $900 million in funding for businesses across trucking, restaurants, retail, construction, and healthcare. Since graduating from the University of Arizona in 2011, Bryan has spent his entire career in alternative finance, helping business owners secure capital when traditional banks turn them away. He specializes in bad credit funding, no doc lending, invoice factoring, and working capital solutions. More about the Clarify team →
Related Posts