 Reviewed by
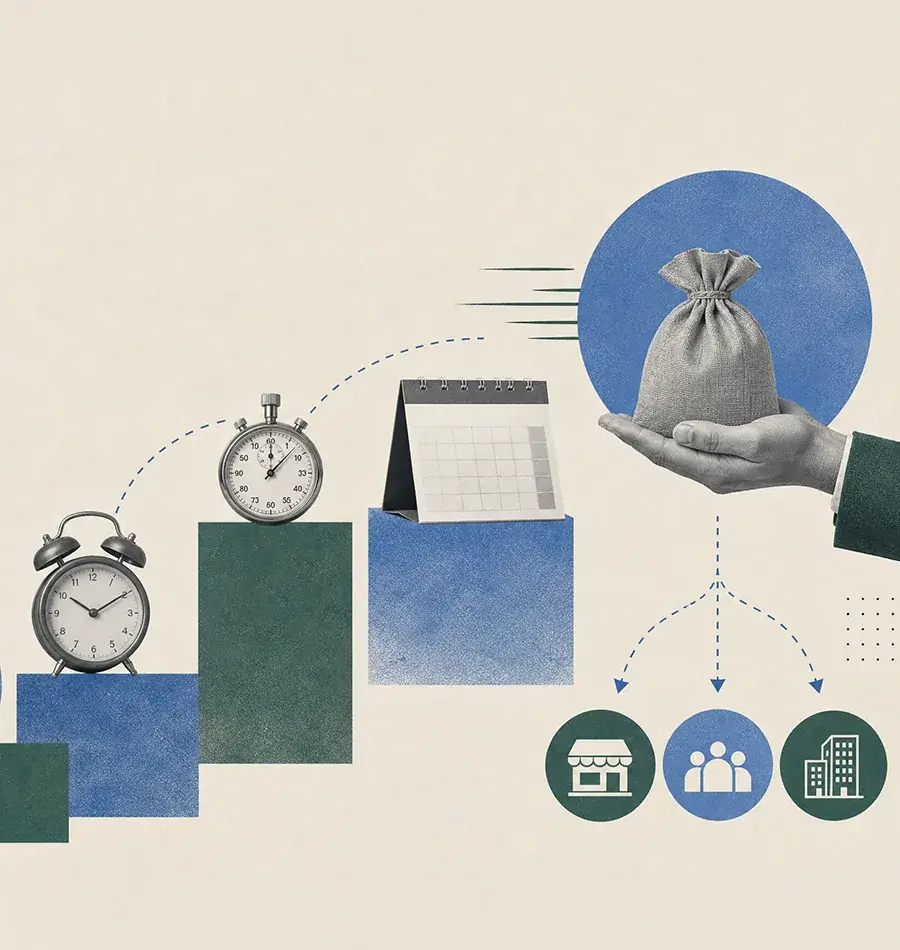
A business loan can close the same day or in three months. The difference depends on who you're borrowing from and what their approval process looks like.
Alternative lenders are often the quickest way to get a business loan, while other options take a bit longer. SBA loans, for example, can close as quickly as two weeks, but typically take 30 to 90 days.
So, how long does it take to get a business loan? In my experience, it depends on how prepared you are. Delays usually happen not because of a lender, but because borrowers haven't organized their documents properly.
Below, I get into exactly how long it takes to get a business loan. I'll cover each stage of the process and what you need to know for a successful application.
| Financing type | Time to financing | What the lender reviews |
|---|---|---|
| Short-term business loan | As fast as same day | Three to four months of bank statements, no collateral |
| Business line of credit | As fast as same day | Three to four months of bank statements, no collateral |
| Merchant cash advance | As fast as same day | Three to four months of bank statements, repaid from future sales |
| Equipment financing | One to five days | Bank statements plus a quote for the equipment, which serves as the collateral |
| Home equity line of credit | As fast as one week | Income verification, pay stubs, tax returns, bank statements, and qualifying real estate |
| Invoice factoring | One to two weeks | Your invoices and your customer's credit, with the invoice itself as the asset |
| SBA loan | As fast as two weeks, typically 30 to 90 days | Tax returns, financial statements, and bank statements, with collateral sometimes required |
The Four Steps of a Business Loan Timeline
The steps below detail how the process typically goes when applying for a small business loan.
Step 1: Application
Pay close attention to the lender requirements. Lenders ask for tax returns, financial statements, balance sheets, pay stubs, income verification, and bank statements. Preparing your documents in advance helps to make sure the application process goes smoothly.
Step 2: Underwriting Process
At this point, the lender starts reviewing your financial documents, checking your credit report, and seeing if your monthly cash flow covers the loan payments. Applications for smaller loan amounts are typically processed more quickly than larger ones.
Step 3: Approval and Offer
The time from underwriting to an offer depends on the type of loan you're applying for and the lender. SBA loans fund as quickly as two weeks, but typically take 30 to 90 days. By comparison, business lines of credit can finance as fast as same day.
Step 4: Disbursement
Disbursement timelines vary based on the type of financing. The money can land in your bank account the same day as approval for a short-term business loan, a business line of credit, or a merchant cash advance. Equipment financing takes one to five days.
What Slows a Business Loan Down
Here are the most common reasons I see small business owners experience slowdowns during the application process.
Incomplete financials
It's a red flag to lenders when your profit and loss statements don't match your tax returns.
Unfiled tax returns
Most lenders won't underwrite your application without a tax return.
Existing liens
A prior Uniform Commercial Code (UCC) filing can mean that a lender may not be able to file a new one, which limits their ability to get collateral for a new loan.
Ownership changes
When there are changes made to the ownership structure of your company, your application eligibility review starts again.
Collateral appraisal
Plan in advance for an outside appraiser to value all real estate or equipment.
Undisclosed existing debt
Waiting too long to disclose debt can hurt your credibility and cause delays in the application process.
Minimum Qualifications
For Financing Through Clarify Capital

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
The Fastest Business Financing Options
There are three different financing options available through Clarify Capital's network of 75+ vetted, reputable lenders that provide same-day financing.
Short-term business loans. These are a single lump-sum payment from $10,000 to $5 million. These work for big purchases; interest rates start at 6% with repayment terms spanning six to 36 months.
A business line of credit. A revolving credit line up to $5 million with APRs starting at 6%. You only pay interest on what you use.
Merchant cash advances. Borrow a percentage of your monthly sales up to $5 million. These are priced using a factor rate ranging from 1.08 to 1.45.
How To Get Faster Financing
Nothing here requires a different business. It only requires a different order of operations.
Gather your documents
Organize at least three to four months of bank statements, your most recent tax returns, and financial statements before submitting an application.
Keep your filings current
A missed tax return or an unreconciled month of bank statements will cause delays in processing.
Explain a revenue dip
Lenders understand seasonal fluctuations or lost contracts, but without the explanation, these are seen as risks.
Loan amount and how you'll use it
A quote for equipment based on a dollar amount moves through the process much faster than one without.
Match the lender to your profile
Applying for the financing option that matches your business needs speeds up the process.
Respond to lender questions quickly
Each day a lender request sits in your email is another day added to the overall processing time.
A business plan also helps speed up the process, though it matters more for SBA lenders and traditional banks than alternative lenders.
Working Backward From Your Deadline
Work backward from when you need the money. Being short two weeks before payday and needing money for a piece of equipment six months down the road call for different financing options.
I see people chase the cheapest interest rate all the time. But that isn't always the right option.
Apply today and see what a small business loan looks like against your calendar. Checking your options won't affect your credit score.
Frequently Asked Questions
These are the most common questions I get on small business loan timelines.
How Long Does a Bank Take To Approve a Business Loan?
It depends on the lender, but in general, banks usually take anywhere from two to six weeks to approve a small business loan.
How Quickly Can I Get a Small Business Loan?
As fast as same day. If you apply through an alternative lender and your banking records are current, you can often receive financing in a day or so.
Why Do SBA Loans Take So Long?
SBA loans take so long because there are two levels of review. First, your lender underwrites your loan package. Then, the Small Business Administration (SBA) reviews and approves your loan package. The SBA's normal turnaround time for approving a 7(a) loan is five to 10 business days. Closing your loan requires additional time to ensure everything is properly cleared.
Does Applying to Several Lenders Slow Things Down?
It slows down the process when you apply to lenders one after the other. Each lender's approval timeline begins after the previous lender has either approved or denied your application. Using a broker lets you submit your application to multiple lenders simultaneously, so you can compare different offers at once.
Is My Information Safe When I Apply Online?
Clarify follows SOC 2 security principles, which cover how we store, encrypt, and control access to applicant data. Here's how lenders handle your data.
Michael Baynes
Co-founder, Clarify
Michael has over 15 years of experience in the business finance industry working directly with entrepreneurs. He co-founded Clarify Capital with the mission to cut through the noise in the finance industry by providing fast funding and clear answers. He holds dual degrees in Accounting and Finance from the Kelley School of Business at Indiana University. More about the Clarify team →
Related Posts