Private business loans

Compare the Best Private Business Loan Offers — Get Funded in 24 Hours

Learn how private business loans work, how they compare with bank and SBA financing, what they can cost, and what to check before signing.

  • Private business financing can offer faster access and more flexible underwriting than traditional bank loans, but it may come at a higher cost.
  • Options include term loans, lines of credit, equipment financing, invoice factoring, merchant cash advances, and private-investor capital.
  • Compare the full cost of financing, including APRs, factor rates, fees, repayment frequency, and total repayment, rather than just the headline rate.
  • Before signing, review the lender, personal guarantees, prepayment terms, required disclosures, and whether the repayment schedule fits your cash flow.
See Loan Options
Won't impact your credit
Bryan Gerson
Written by
Bryan Gerson
Compare the Best Private Business Loan Offers — Get Funded in 24 Hours

Rated 5 Stars on Google

Business owners with less-than-stellar credit love us because we treat them like family.

Quick application

Your time is valuable. Our online application takes just 2 minutes to get approved.

Dedicated loan advisors

We do all the paperwork and you get money in your bank account the same day.

I've been working in the lending industry for more than a decade, and a situation I tend to see a lot is a small or midsize business (SMB) owner in need of capital getting turned down by a bank, or getting approved but realizing the bank's timeline is too slow for their specific capital need.

That's when I tend to tell clients to consider private financing. The term “private business loan” can be a deceptively broad one in the lending world. It includes loans that come from non-bank lenders, private investors, and sometimes private banks. And, importantly, each of those options can work a little differently when it comes to how fast you receive the money, the total cost of borrowing, and the repayment structure.

It's useful for an established business that needs flexibility and/or faster funding than what a bank can provide. That said, the speed and access tend to mean it comes at a higher borrowing cost.

Here I'm going to break down what private business loans are, as well as how they compare to other funding options (including bank and SBA loans), what they can cost, and what to watch out for to avoid nefarious lenders. I'll also show you how you can apply for private financing, if and when you're ready, with Clarify Capital.

Lender typeTypical funding speedApproval barCostBest for
Private or non-bank lenderAs quickly as same day for some financing types, depending on the financing type and lenderMay be more flexible on credit or business history, but still evaluates ability to repay. Online lenders at least partially approved 70% of medium- and high-credit-risk applicants, vs. 54% at large banks.Often higher than bank financing, pricing and repayment structures vary widely by financing typeEstablished businesses that value speed or flexibility and can support the higher potential cost
BankUsually more documentation-heavy and may take longer; three in four banks approve their typical small-business loan within 10 business daysGenerally, stronger credit, cash flow, financial history, and documentation expected. Small banks fully approved 57% of applicants, while large banks fully approved 43%.Often lower-cost than online or alternative financing for well-qualified borrowersEstablished businesses with strong financials that can wait through a more traditional underwriting process
SBA loanAs quickly as two weeks, but typically 30 to 90 daysGenerally, more documentation and underwriting, with repayment ability and program eligibility closely reviewedOften comparatively favorable because SBA guarantees reduce some lender riskBusinesses that qualify and can wait longer for financing in exchange for potentially better terms
Private equity investorVaries widely based on finding an investor, negotiating terms, and completing due diligenceBased more on the business's growth potential, management, market opportunity, and investment fit than standard loan underwritingMay not involve interest at all, but can require giving up equity, future profits, control, or other economic rightsBusinesses willing to exchange ownership or other rights for capital rather than take on conventional debt

What Private Business Loans Actually Are

As I mentioned earlier, private business loans aren't really one type of loan, but actually a broad category of loans. It can be capital from a non-bank lender (like an online platform), a private investor, or, in some cases, a private bank. And that capital can come in several forms. These are some common ones:

Type of private fundingHow it worksWhat it's best for
Term loanA lump sum you repay over a set period, usually with regular paymentsOne-time expenses when you know how much capital you need up front and want a set repayment schedule
Invoice factoringYou sell eligible unpaid invoices to a factoring company in exchange for faster access to cashB2B businesses with unpaid customer invoices that need cash before those invoices are paid
Business line of creditRevolving financing you can draw from, repay, and use again as neededOngoing or recurring expenses like inventory, payroll gaps, and short-term working capital needs
Equipment financingFinancing tied specifically to an equipment purchase, with the equipment typically serving as collateralBuying or replacing business equipment when you want the purchase itself tied to the financing
Merchant cash advanceA lump-sum advance that is repaid from future business salesBusinesses with consistent sales that need fast access to capital and can handle frequent repayment

Usually, when people talk about private business lending, they're talking about non-bank lenders. In the Federal Reserve's 2025 survey, 29% of small employer firms seeking a loan, line of credit, or cash advance applied to an online lender, up from 17% in 2020. These companies are attractive to some business owners because they're usually able to move faster or have more flexible underwriting than a bank.

Private investors work a little differently. Instead of a typical loan structure, they'll usually give a business money in exchange for equity in the business (aka partial ownership), profit participation, or other financial rights. Basically, you won't have to repay the loan via payments, but you could be giving up part of the company or some future upside in return for the capital

What Private Lenders Look for in Applicants

Because there are so many different types of private business loans, lenders have different qualification requirements and underwriting methods based on both their own policies and the structure of the loan or funding. Still, generally, they will want to see a few key things when assessing your business that will indicate to them that you'll be able to repay what you borrow. Some of those things include:
Credit profile

Credit profile

Your personal and business credit can help lenders gauge how you've handled debt in the past, although some private lenders are more flexible than banks when credit is less than perfect.
Revenue and cash flow

Revenue and cash flow

Lenders want to see enough consistent income coming into the business to support the payment without putting too much pressure on day-to-day operations.
Time in business

Time in business

A longer operating history gives lenders more financial information to evaluate and can make your revenue patterns easier to assess.
Existing debt

Existing debt

Current loans, credit lines, leases, and other obligations can affect how much additional debt a lender thinks the business can reasonably take on.
Collateral

Collateral

Depending on the financing type, business equipment, receivables, real estate, or another asset may help secure the financing and reduce the lender's risk.
Documentation

Documentation

Expect lenders to review records such as bank statements, tax returns, financial statements, or other documents that help verify the business's finances.

The emphasis or weight a lender puts on each of those things varies by the type of loan or financing you're specifically asking for. Invoice factoring, for example, puts much more emphasis on the quality of your receivables and your customers' ability to pay, while equipment financing is tied more directly to the asset being purchased.

Clarify Capital fits into the private financing space as a broker and marketplace, but not as the lender itself. If you work with my team and me, these are the general requirements we want your business to have in order to get started on helping you find lenders:
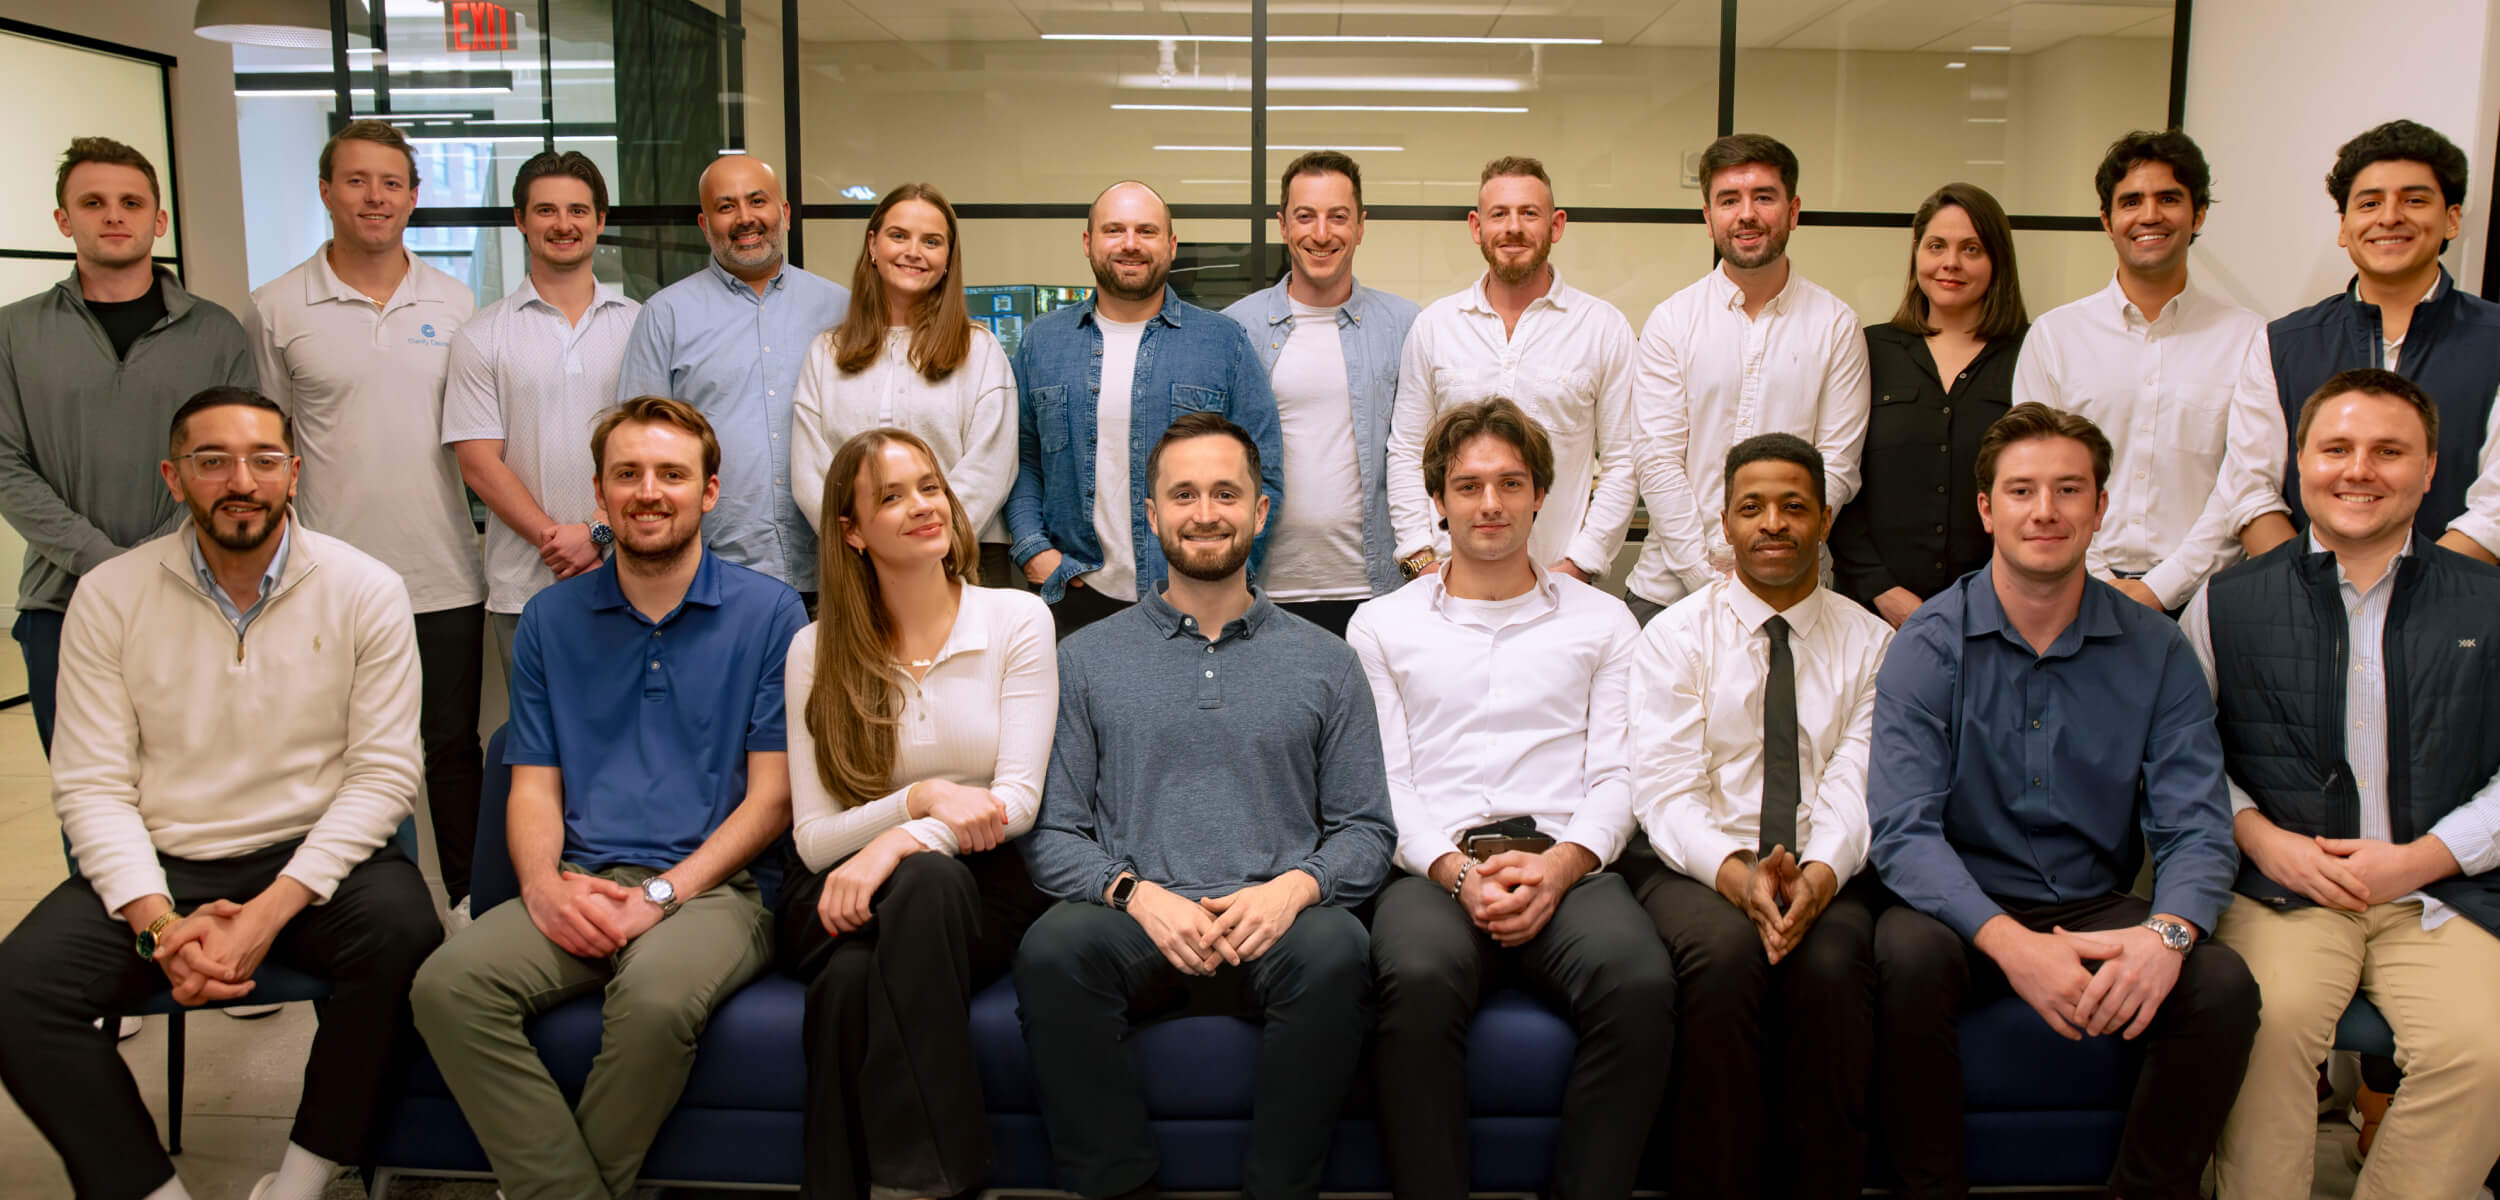
Meet your Clarify advisors

Clarify Capital fast business loan advisors

We make sure you're getting the best private business loan terms, and set your company up for growth. See how it works →

$

Your Minimum Requirements

There are basic things you need to qualify for a private business loan. Your Clarify advisor will guide you through the process, even if you have bad credit. Exact eligibility requirements can vary by private lender and loan option, but Clarify Capital helps streamline underwriting and matches you with private business lenders that fit your profile.

Monthly revenue

At Least $10K in Monthly Sales

Your business must be making over $10K per month in revenue and cash flow that can support repayment.

Credit score

At Least a 500 FICO Score

You can get approved with any credit score. But the higher your score, the better the loan terms and the lower the monthly payments from online private lenders.

Time in business

Your Business Is at Least 6 Months Old

Your company should be operational for six months at a minimum. This shows lenders that your business is sustainable and won't default on the loan.

Business bank account

Have a Business Bank Account

Your Clarify advisor will require three to four months of your most recent bank statements from a business bank account or dedicated business checking account to verify business revenue.

Start Application

Small Businesses ❤️ Clarify

What Private Financing Can Cost

Plain and simple, private financing is usually going to cost more than more traditional-style loans. And that's basically because you're paying for faster funding and more flexible underwriting.

Among businesses that borrowed from online lenders, 60% said their actual borrowing costs were higher than they expected, compared with 37% at small banks and 32% at large banks.

The total cost of a private loan is going to hinge heavily on the structure of the specific type of financing you're interested in. For example, term loans, business lines of credit, and equipment financing usually use APR, while merchant cash advances use what's called a factor rate, and invoice factoring has a factoring fee.

Pricing methodHow it works
APRExpresses the annualized cost of borrowing, including interest and certain fees, which makes it easier to compare loans with similar structures.
Factor rateMultiplies the amount advanced by a fixed number to determine the total repayment. A $100,000 advance with a 1.25 factor rate, for example, means $125,000 must be repaid.
Factoring feeCharged against the value of an invoice, often based on how long the customer takes to pay. The longer an invoice remains outstanding, the more the financing can cost.

Let's say you get a $100,000 short-term loan with a 12% annual interest rate and repay it over three years. You'd end up repaying around $119,570 in total (so about $19,570 in interest) with monthly payments of about $3,321. If you got a $100,000 merchant cash advance with a 1.25 factor rate, your total repayment would be $125,000. That's a significantly higher borrowing cost.

To compare things evenly when you're between different types of financing, always go over the amount you receive, the total amount you'll repay, how often payments are due, and whether there are additional origination, draw, servicing, or prepayment fees.

When Private Financing Isn't the Best Fit

I think going the private route makes the most sense when you have an established business that has enough cash flow to handle payments comfortably, and getting the money quickly is a priority for some specific business purpose.

If you have borderline-strained or strained cash flow, it's probably not a good idea. And if you have the time and financial strength to possibly qualify for a lower-cost borrowing option (like a regular bank loan or an SBA loan), I'd advise you to do that.

Here are some pros and cons to help you decide what's right for your business:

Pros

Pros

  • Faster access to capital. Some private financing options can move much faster than traditional bank financing, which can help when you're dealing with a time-sensitive expense or opportunity.
  • More flexible underwriting. Private lenders may consider factors like revenue, cash flow, collateral, and time in business alongside your credit profile.
  • More financing options. You can choose from term loans, lines of credit, equipment financing, invoice factoring, MCAs, and other structures depending on what you're financing.
  • Useful when a bank isn't the right fit. Private financing can give established businesses another option when a bank says no or the traditional process takes too long.
Cons

Cons

  • Potentially higher cost. Private financing can cost more than traditional bank or SBA financing, especially when you're paying for speed or more flexible underwriting.
  • Shorter repayment periods. Some financing options require repayment over a shorter period, which can increase the amount you need to pay each week or month.
  • More frequent payments. Depending on the financing type, payments may be due daily or weekly instead of monthly, which can put more pressure on cash flow.
  • Terms vary widely. Costs, collateral requirements, guarantees, fees, and repayment structures can differ substantially from one lender and financing type to another.

Red Flags in Private Lenders

Unfortunately, not every private lender is going to have your best interests at heart. The range of financing structures out there in this category means you need to closely scrutinize any agreement before you sign it. Some of the biggest red flags to look out for are:

Unclear total repayment

Unclear total repayment

You should be able to tell how much money you'll actually receive and how much you'll repay in total, including fees

Pressure to sign quickly

Pressure to sign quickly

Be cautious if a lender discourages you from reviewing the agreement, comparing offers, or having an attorney or advisor look at it

Surprising prepayment terms

Surprising prepayment terms

Paying early doesn't always reduce the cost. Check whether prepayment saves you money, triggers a fee, or leaves most of the original finance charge in place

Broad personal guarantees

Broad personal guarantees

A personal guarantee can make you personally responsible for the business's obligation, so understand exactly what you're agreeing to and when the lender can enforce it

Fees that aren't clearly explained

Fees that aren't clearly explained

Watch for origination, broker, servicing, draw, renewal, or other fees that materially change the cost from the headline rate

Missing or inconsistent lender information

Missing or inconsistent lender information

Verify who is actually providing the financing, who you'll make payments to, and whether any required state registration or license can be confirmed

Legal Disclosures

Several states have commercial-financing disclosure laws (including California, New York, Florida, Utah, Kansas, Missouri, Connecticut, and Virginia), but they vary. If you're doing business in one of those, make sure you receive those disclosures and read them thoroughly.

California, for example, requires lenders to disclose total funds provided, total dollar cost, payment terms, and prepayment policies, while Florida and Kansas similarly require providers to disclose core transaction costs and payment details.

Alternatives to Fast Business Loans

Here are common alternative funding options that we've provided business owners. Your loan advisor will guide you through all options so you can make the best decision.

$

You deserve low rates and an honest private lender who has your back.

From our humble beginnings in 2018, we remain committed to helping American businesses achieve success. We keep private lending simple, convenient and transparent. Read our manifesto →

How to get a private business loan

Why Work With Clarify Capital?

My company, Clarify Capital, has a 5.0 Trustpilot rating (the highest in the industry). Our approach is to pair every applicant with their own dedicated U.S.-based lending advisor, rather than a chatbot or call center, to help you compare options from our network of 75+ vetted lenders. Apply today.

Apply online
Step 1:Apply online

It takes about two minutes. You'll need your business's legal name, EIN, time in business, monthly revenue, requested loan amount, owner contact information, and a credit authorization.

Apply here

Connect with a lending advisor
Step 2:Connect with a lending advisor

A U.S.-based Clarify Capital lending advisor reviews the application, runs a soft credit pull (no impact to your score), and requests 3 to 4 months of recent business bank statements.

Get matched and funded
Step 3:Get matched and funded

Clarify Capital works with 75+ vetted lenders and matches your profile with the right financing. Approvals often get a same-day offer (SBA loans can take longer).

Frequently Asked Questions

In my opinion, one of the easier small business loans to get is a short-term loan from an online lender. They tend to have fewer documentation requirements, faster approval times, and more flexible criteria than banks or SBA lenders.

It depends on what type of loan or financing it is. Let's use a short-term loan as an example. If you borrowed $100,000 at a 12% annual interest rate and repaid it over three years, you'd end up repaying roughly $119,570 in total (so about $19,570 in interest).

Usually you'll need more than your EIN alone. Lenders want to see things like your business's revenue and cash flow, credit profile, time in business, existing debt, and financial documentation to be able to assess whether you're a good candidate who can repay what you borrow.

Yes, if you use a legit and vetted lender. Avoid working with a company/lender if they're sort of vague about costs, focus a lot on how quickly they can get you the money, push you to sign fast, or can't clearly explain exactly how repayment works.

Clarify Capital follows System and Organization Controls 2 (SOC 2) security principles that protect sensitive business and financial information, including secure data handling practices, controlled access to information, and ongoing monitoring to help protect your data throughout the application and funding process.


Apply for fast business loan

Ready for a private business loan?

Get quick online approval with APRs starting at just 6%. Flexible repayment options available for credit scores over 550. Won't affect your credit!

$