 Reviewed by
Business lenders advertising same-day, no-credit-check business loans typically use a soft credit pull to view your report. This means they can view your credit history without lowering your rating.
I've spent my career helping small and midsize business owners navigate the financing process, and below I'll outline how to bypass the hard credit inquiry process.
I'll also cover the fees associated with each type of financing, and explain what factors lenders consider most when your credit score isn't the primary decider.
| Financing option | Credit inquiry | What it's underwritten on | Speed to funding | Typical cost |
|---|---|---|---|---|
| Short-term business loan | Usually soft | Monthly revenue and time in business (no collateral required) | As quickly as same day | APR starting at 6% |
| Business line of credit | Usually soft, hard with some lenders | Revenue and account activity (revolving, no collateral required) | As quickly as same day | APR starting at 6%, charged only on what you draw |
| Equipment financing | Soft or hard, varies by lender | The equipment, which serves as collateral | 1 to 5 days | APR starting at 6% |
| Merchant cash advance (MCA) | Usually soft | Future sales, repaid as a share of revenue | As quickly as same day | Factor rate of 1.08 to 1.45 (a multiplier on the amount advanced) |
| Invoice factoring | Usually soft | Your customer's credit and the unpaid invoice | 1 to 2 weeks | 0.5% to 5% per invoice per month |
Hard Credit Pull Vs. Soft Credit Pull
There are two kinds of credit checks: a hard credit inquiry and a soft credit pull.
A hard credit inquiry is a formal review of your credit report that's usually attached to an application for a loan, credit card, or mortgage. Credit bureaus keep these inquiries for up to two years, though FICO typically reviews inquiries from the previous 12 months when calculating your credit score.
A soft credit check is also a review of your credit, but without an application attached. It's the same thing that happens when you check your own credit report, and it doesn't affect your credit score.
When a lender says they offer same-day business loans with no credit check, that doesn't mean they don't look at your score at all. It usually means they're performing a soft credit pull to get a better sense of your creditworthiness.
The hard credit check often comes later, once you're approved for financing.
No Credit Check Vs. No Doc Business Loans
These are two different types of financing I often see borrowers confuse. One is about the credit inquiry, while the other is about the paperwork.
Business loans can be no credit check, no doc or low doc, or both. Here are the differences:
No-credit-check business loans
The lender runs a soft credit pull. The hard inquiry comes once you're approved.
No-doc business loans
Usually means low doc. Lenders look at bank statements instead of tax returns and other financial statements to approve you.
Understanding Your Credit Score
Even when a lender is performing a soft credit pull, your personal credit score still shapes the amount and type of financing you can get approved for.
Here's a full picture of the credit score ranges and what's realistically available at each level. Better scores typically unlock better interest rates and repayment terms.
| Personal credit score | What's realistically available | What else lenders want to see |
|---|---|---|
 | Every option: traditional bank loans, SBA loans, unsecured lines of credit, and the longest terms, with the widest lender choice | Consistent revenue and clean statements; at this level, a strong score speeds approval more than it changes what's required |
 | The full menu, from SBA loans to unsecured lines of credit, with strong approval odds | Steady deposits and a solid operating history, with light documentation |
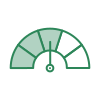 | Broad access, including SBA loans, term loans, business lines of credit, and equipment financing | Three to six months of bank statements and a year or more in business |
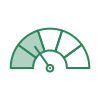 | Short-term loans, equipment financing, merchant cash advances, and invoice factoring across the band; lines of credit from a 600 score and SBA loans from 640 | Strong monthly deposits, steady revenue, and sometimes collateral |
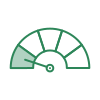 | Invoice factoring and revenue-based options from alternative lenders; merchant cash advances from a 500 score, and short-term or equipment financing from 550 | A revenue minimum, a personal guarantee, and proof you can cover repayment |
If you have a low credit score, bad credit business loans like invoice factoring and equipment financing may still be an option. These are secured by an asset (your unpaid invoices or your equipment), which lenders view as less risky. For small business loans under $50,000 and startups, SBA Microloans are worth a look, though they take a while to fund.
What Lenders Check Instead Of Your Credit
When your credit score isn't the barrier to entry, lenders consider other factors, like regular deposits in a business bank account. Here's what else matters:
Monthly revenue
Revenue-based financing is usually based on the amount you bring in monthly. Lenders also look at your annual revenue.
Deposit consistency
Lenders look for steady deposits in your business bank account, not just big money once a quarter.
Time in business
Most lenders ask for at least six months of operating history for fast funding.
Bank account health
Lenders view overdrafts, negative balances, or bounced payments as a risk.
Most loans still include a personal guarantee, which means you're personally responsible if the business can't pay.
Minimum Qualifications
For Financing Through Clarify Capital

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
How To Spot a Predatory Lender
Same-day funding sometimes attracts lenders who don't have your best interests at heart. Here's what to keep an eye out for.
Guaranteed approval
Guaranteed approval should be an immediate red flag. Legitimate lenders need to review your creditworthiness.
Fees before an offer
Up-front application and processing fees are always a red flag.
A hidden effective rate
Ask for the equivalent annual percentage rate (APR) in writing. Factor rates may seem reasonable but could equal a triple-digit interest rate.
A small daily payment as the headline
How much does that amount add up to by the end of the loan period? Low daily payments could be an expensive way to borrow.
Stacking
Layering multiple advances can grow your debt burden quickly.
A confession of judgment
Ask if the contract contains a confession of judgment clause. This lets lenders get a court judgment against you without a trial if you default.
More states are requiring lenders to make an APR equivalent known from the start for options like MCAs so it's easier to understand what you owe over the life of the financing.
What To Do Next
A same-day business loan with no credit check usually means a soft credit pull. If you have bad credit, revenue-based financing approves you based on other factors like your business bank account.
When you're ready to apply for financing, Clarify Capital runs a soft credit pull and puts your application in front of 75+ vetted, reputable lenders. See what your business qualifies for and apply today.
Frequently Asked Questions
Here's what you need to know about same-day business loans with no credit check.
Can I Get a Business Loan With No Credit Check?
A no credit check usually means a soft credit pull and a hard credit inquiry later. When a lender says they offer same-day business loans with no credit check, that doesn't mean they don't look at your score at all. It usually means they're performing a soft credit pull to get a better sense of your creditworthiness.
Can I Get a Business Loan With Just My EIN Number?
Rarely. An EIN identifies your business, but most lenders also require bank statements along with a personal guarantee tied to your Social Security number for an unsecured loan. Here's what to know about no-doc loans with an EIN.
Can I Get a Same-Day Business Loan?
A few financing options fund in 24 hours. Merchant cash advances and revolving business lines of credit are typically the quickest. But the timing depends on how quickly you submit your application and bank statements.
Do I Have To Commit to Anything To See My Options?
No. A prequalification runs on a soft credit pull and returns real terms so you can weigh your options before you decide.
Is My Information Safe When I Apply With Clarify Capital?
Yes. We follow SOC 2 security principles to protect your financial and personal data. You can read more about how we protect your data on our security page.
Bryan Gerson
Co-founder, Clarify
Bryan has personally arranged over $900 million in funding for businesses across trucking, restaurants, retail, construction, and healthcare. Since graduating from the University of Arizona in 2011, Bryan has spent his entire career in alternative finance, helping business owners secure capital when traditional banks turn them away. He specializes in bad credit funding, no doc lending, invoice factoring, and working capital solutions. More about the Clarify team →
Related Posts