 Reviewed by
The rate quote you receive when trying to get a home equity line of credit (HELOC) is usually determined by a few combined factors: credit score, desired borrowing amount, home value, equity you own in your home, debt load, and property type/occupancy status.
A good rate for someone with a lot of equity and strong credit and finances is therefore different from what a good rate would be, comparably, for someone with just enough equity and weaker finances.
In general, though, a rate that's in the low-7% range is pretty much in line with the bigger market right now. For reference, the national HELOC benchmark rate as of early September 2026 for borrowers with a 700 FICO credit score, an 80% loan-to-value (LTV) ratio, and a $30,000 line of credit is 7.26%.
HELOC rates are usually an underlying index plus a margin that's set by your lender. And many lenders use the variable U.S. prime rate as that underlying index, which is 6.75% (as of early September 2026). So a 6.75% prime rate + a roughly 0.51% average margin from lenders = the 7.29% benchmark I just mentioned.
I have 15 years of experience helping small to midsize business owners get financing, so I talk to a lot of entrepreneurs who are weighing using home equity versus business financing to help them grow or cover expenses. If that's you, here's my advice: rate alone shouldn't be your only deciding factor in whether you get a HELOC.
If you were my client, the bigger question I'd push you to consider is whether borrowing against your home gives you a better overall deal than financing with another funding type, like a business line of credit or term loan.
A HELOC may come with a lower borrowing cost, but that's because your home backs the debt, which means a much bigger personal consequence if, for some reason, the business can't make payments down the road.
Here, I'll explain more about where HELOC rates currently sit, what can move your rate up or down, and how to decide whether tapping your home equity actually makes sense for your business.
| FICO score range | FICO classification | How lenders may view the score | HELOC takeaway |
|---|---|---|---|
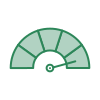 | Exceptional | Lowest credit risk range | Strong credit, but rate still depends on CLTV and other underwriting factors; don't assume the first quote is your best; compare rates, margins, and fees |
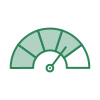 | Very Good | Above-average credit profile | Strong score for rate shopping; compare lenders because pricing can still differ despite strong credit |
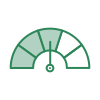 | Good | Generally solid credit profile | A 700 score falls here and is the basis of the current 7.29% benchmark |
 | Fair | Greater credit risk | HELOC options may be more limited and other qualifications become especially important |
 | Poor | Highest-risk FICO category | Finding a HELOC may be difficult depending on the lender |
How HELOC Rates Have Changed in 2026
HELOC rates have gone down a bit recently, but modestly. Again, we can tell because of the national HELOC benchmark: On September 2, 2026, it was 7.29%, which was down from 7.44% on August 5. That's a decline of 15 basis points in about a month, but remember that things can always change quickly.
| Date | National HELOC Benchmark Rate |
|---|---|
| Aug. 5, 2026 | 7.44% |
| Aug. 12, 2026 | 7.30% |
| Aug. 19, 2026 | 7.31% |
| Aug. 26, 2026 | 7.30% |
| Sept. 2, 2026 | 7.29% |
Just be careful when comparing that benchmark with rates you see advertised. Some lenders offer introductory rates that only apply for a limited period, so look at the ongoing variable rate, margin, and fees when deciding whether an offer is actually competitive.
Homeowners are also using more of their available equity. According to the New York Federal Reserve, outstanding HELOC balances reached $459 billion in Q2 2026, up $13 billion from the previous quarter and marking the 17th consecutive quarterly increase.
Why Your HELOC Rate Is Higher or Lower
Your HELOC margin is set by your lender based on the risk they deem you to be as a borrower and the line of credit they offer. All of them will price things differently, but in general, these are factors that can push your rate up or down:
| Credit score | A higher score can help you qualify for a lower margin, while weaker credit can result in a higher rate; there's no standard adjustment for moving from one FICO tier to another |
|---|---|
| Combined loan-to-value (CLTV) ratio | A lower CLTV generally works in your favor because you're borrowing less against your home's value; higher CLTVs can mean higher pricing or tighter eligibility requirements |
| Debt-to-income ratio (DTI) | A lower DTI shows that less of your income is already committed to debt and can help with pricing |
| Line and draw size | How much credit you request (and in some programs, how much you initially draw) can affect the margin you're offered; the direction and size of the adjustment depend on the lender |
| Occupancy and property type | Primary residences generally present a different risk profile than second homes or investment properties, while condos and other property types may face different CLTV limits or underwriting |
| Type of lender | It pays to compare banks and credit unions; as of December 2025, the average rate on an 80% LTV HELOC was 7.13% at credit unions versus 7.74% at banks |
Remember here that none of these factors work alone. Lenders tend to take a more holistic view of all of them combined, so a great credit score doesn't necessarily guarantee the lowest rate if you're borrowing close to your home's equity limit, and vice versa.
Another thing to note is that some HELOCs let you convert some or all of a variable-rate balance to a fixed rate, while others may come with application, appraisal, annual, transaction, inactivity, or early-termination fees. These differences can affect what you ultimately pay even when two lenders advertise similar rates.
Your HELOC Rate Seems High: What Now?
If the first HELOC rate quote you get surprises you compared with the benchmarks I discussed earlier and your qualifications, there are a few things I recommend you try and do to get a lower rate:
Boost your credit score
If you're close to the next credit-score tier, improving your score may help you qualify for better pricing
Borrow less against your equity
Ask whether requesting a smaller line would put you in a lower CLTV bracket and improve your pricing (especially if you're close to one of your lender's pricing cutoffs)
Compare banks and credit unions
Don't assume the first lender is competitive; get multiple quotes at once
Ask what can be waived
HELOCs can carry application, appraisal, annual, inactivity, and other fees; some lenders waive certain up-front costs, so it doesn't hurt to ask
When a HELOC Makes Sense for Business Costs
HELOCs often come with a lower interest rate and flexible access to capital as you need it. But a business loan (which is a broad term that can include a lot of different financing options) avoids putting your home on the line as collateral, is often more flexible on eligibility, and may get you money more quickly.
The right option when considering these two financing paths specifically is going to depend on your tolerance for higher costs, appetite for risk, and, of course, you and your business's financial eligibility. To visualize this, let's compare HELOCs with two other common business financing:
| Secured by | Typical borrowing limit | Rate range | Best for | |
|---|---|---|---|---|
| Clarify Capital's home equity line of credit (HELOC) for Businesses | Equity in the business owner's residential property | Based on available home equity; up to $750,000 | As low as prime; often prime + lender-set margin with most lenders | Business owners with home equity who want relatively low-cost, longer-term capital and are comfortable securing it with their home |
| Term loan (short or long-term) | Varies by lender and loan; may be secured or unsecured | $10K to $5M | APR from 6% | One-time, defined expenses where you know how much you need up front |
| Business line of credit | Generally based on the business's creditworthiness and cash flow; collateral requirements vary | $5K to $5M revolving | APR starting at 6%; only pay interest on what you draw | Recurring expenses, seasonal cash-flow gaps, inventory, and other short-term or unpredictable needs |
A HELOC for business financing can make sense if you have strong home equity, steady business revenue, and a clear plan for the money, plus want a lower rate than other types of business financing and are comfortable with the risk. And since a HELOC is a revolving line of credit, it tends to be especially helpful for covering costs where you don't know exactly how much you'll really need.
For example, I've seen small and midsize business owners use HELOCs for:
Opening a new location
Cover expenses such as renovations, furniture, signage, deposits, or other costs associated with expanding into another location.
Buying equipment or inventory
Purchase equipment or stock up on inventory without necessarily drawing your entire available credit line at once.
Managing a slow season
Help cover payroll, rent, utilities, or other operating expenses when revenue temporarily slows.
Consolidating higher-cost debt
Pay off higher-cost business debt if the HELOC offers a lower rate, potentially reducing financing costs.
When it comes to business expenses, a HELOC probably isn't the right move when you're borrowing to cover ongoing losses or anything the business could carry the debt on its own credit. It's also not right if you don't have a clear repayment plan or think there's any chance you couldn't comfortably make payments if business revenue temporarily declined.
Why Business Owners Work With Clarify
Clarify Capital offers HELOCs for businesses. When you're ready, my team and I can help you review your qualifications, rate quotes, or explore more options. Get started and apply today. Here's how the process works:
Step 1:Apply online
It takes about two minutes. You'll need your business's legal name, EIN, time in business, monthly revenue, requested loan amount, owner contact information, and a credit authorization.
Step 2:Connect with a lending advisor
A U.S.-based Clarify Capital lending advisor reviews the application, runs a soft credit pull (no impact to your score), and requests 3 to 4 months of recent business bank statements.
Step 3:Get matched and funded
Clarify Capital works with 75+ vetted lenders and matches your profile with the right financing. Approvals often get a same-day offer (SBA loans can take longer).
Clarify Capital's 5.0 Trustpilot rating is the highest in the industry, and we've placed more than $1 billion across 50,000+ small-to-midsize businesses (SMBs).
Clarify matches you across 75+ vetted lenders and can get you a written offer in as quickly as 24 hours. Every applicant works with a U.S.-based lending advisor (not a chatbot or a call center) from application through financing.
Minimum Qualifications
For Financing Through Clarify Capital

$10,000 in monthly revenue
Your business must earn at least $10K per month in a business bank account.

500+ credit score
You can get approved with any credit score. But the better your credit rating, the better interest rates lenders offer. Your FICO score should be above 500.

Minimum six months in business
Your company should be operational for a minimum of six months. This shows business lenders that your company is sustainable and won't go out of business.

Have a business bank account
Your Clarify advisor will need three or four months of your most recent bank statements to verify income. This is just to see you're actually making $10K+ month in revenue.
Frequently Asked Questions
How Much Would a $100,000 HELOC Cost Per Month?
Let's break it down with some hypothetical numbers. If you got a $100,000 HELOC at a rate of 8%, you'd pay $667 per month in interest alone (not considering how much you're paying off per month). Remember that HELOCs often have variable rates, so that 8% could rise or fall month to month.
Is a HELOC a Good Idea Right Now?
It depends. Are you comfortable putting your personal home on the line? Do you have sustainable home equity and a strong financial background? Could you comfortably repay what you borrowed, even if your variable rate increases? If you're a business owner intending to use the capital for business purposes, I'd look into other types of business financing before making a decision.
How Is a $50,000 Home Equity Loan Different From a $50,000 Home Equity Line of Credit?
They're often confused with each other, but quite different. With a home equity loan, you usually get the money as a lump sum and then repay it from there. With a HELOC, you get access to a revolving line of credit up to a certain amount, which you can pay off and then borrow again from continuously.
How Does Clarify Capital Protect My Business and Financial Information?
Clarify Capital follows Service Organization Control 2 (SOC 2) security principles that protect sensitive business and financial information, including secure data handling practices, controlled access to information, and ongoing monitoring to help protect your data throughout the application and funding process.
Michael Baynes
Co-founder, Clarify
Michael has over 15 years of experience in the business finance industry working directly with entrepreneurs. He co-founded Clarify Capital with the mission to cut through the noise in the finance industry by providing fast funding and clear answers. He holds dual degrees in Accounting and Finance from the Kelley School of Business at Indiana University. More about the Clarify team →
Related Posts